A bear-case scenario for the long-term, diversified stock market investor 📉
Source: https://www.tker.co/p/bear-case-scenario-for-long-term-stock-market-investors
Nobody likes to see the price of a stock they own go down. But some of the most encouraging stock market stats involve what happens when things go wrong. After Berkshire Hathaway announced Warren Buffett’s retirement, Meb Faber shared this mind-blowing stat. “If Berkshire declined 99% today on the news of Buffett’s retirement, Berkshire would still have outperformed the S&P 500 since 1965,” Faber wrote. (Buffett took over Berkshire in 1965.) Morningstar’s Danny Noonan illustrated this in a log-scaled chart.
자신이 보유한 주식의 가격이 하락하는 것을 좋아하는 사람은 없습니다. 하지만 주식 시장에서 가장 고무적인 통계 중 일부는 상황이 잘못되었을 때 어떤 일이 일어나는지와 관련이 있습니다. 버크셔 해서웨이(Berkshire Hathaway)가 워런 버핏(Warren Buffett)의 은퇴를 발표한 후, 멥 파버(Meb Faber)는 다음과 같은 놀라운 통계를 공유했습니다. 파버는 "워런 버핏의 은퇴 소식으로 오늘 버크셔의 주가가 99% 폭락하더라도, 버크셔는 1965년 이후 S&P 500 지수보다 여전히 우수한 성과를 냈을 것입니다"라고 썼습니다. (버핏은 1965년에 버크셔를 인수했습니다.) 모닝스타(Morningstar)의 대니 누난(Danny Noonan)은 이를 로그 스케일 차트로 시각화하여 보여주었습니다.
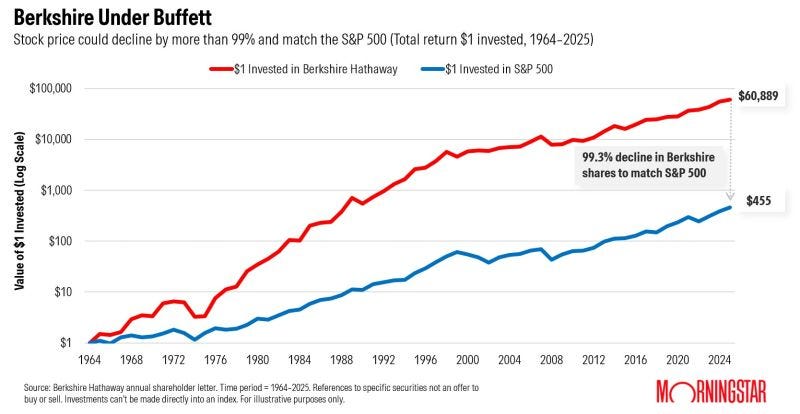
Being able to lose 99% and remain up speaks to the asymmetry of long-term stock market returns. We’ll get back to this in a minute. But first, I know that a stat like this will elicit mixed feelings. So before you get all riled up, let me flag a few issues:
- Cherry-picked winner: Most stocks don’t outperform the S&P 500, so this stat reflects what happens if you’re lucky enough to pick a rare winner. Indeed, Buffett would be the first to tell you that luck plays a huge role in picking market-beating stocks. He’s made clear that the Berkshire equity portfolio’s ”satisfactory results have been the product of about a dozen truly good decisions — that would be about one every five years.“
- One purchase: This stat is about a single hypothetical purchase made in 1965. Most people make purchases over many periods throughout their lifetime. This means a typical investor’s average cost would likely be much higher than the 1965 price, so a 99% decline would be far more costly.
- Long holding period: It’s been 61 years since 1965. Most investors have a shorter time horizon before they have to sell. This includes even young people saving for retirement.
99%를 잃고도 수익을 유지할 수 있다는 점은 장기 주식 시장 수익률의 비대칭성을 잘 보여줍니다. 이에 대해서는 잠시 후에 다시 다루겠습니다. 하지만 먼저, 이러한 통계가 복합적인 감정을 불러일으킬 것임을 잘 알고 있습니다. 따라서 본격적으로 흥분하시기 전에, 몇 가지 짚고 넘어가야 할 문제들이 있습니다.
- 선택된 승자 (Cherry-picked winner): 대부분의 주식은 S&P 500 지수를 상회하지 못합니다. 따라서 이 통계는 드문 승자를 고를 만큼 운이 좋았을 때 어떤 일이 일어나는지를 반영합니다. 실제로 버핏은 시장을 능가하는 주식을 고르는 데 운이 엄청난 역할을 한다는 점을 가장 먼저 강조할 인물입니다. 그는 버크셔의 주식 포트폴리오가 거둔 "만족스러운 결과는 진정으로 훌륭한 십 여 개(약 5년에 한 번꼴)의 결정 덕분이었다"고 명확히 밝혔습니다.
- 단 한 차례의 매수 (One purchase): 이 통계는 1965년에 이루어진 단 한 번의 가상 매수를 전제로 합니다. 대부분의 사람들은 평생에 걸쳐 여러 시점에 걸쳐 주식을 매수합니다. 이는 일반적인 투자자의 평균 매단가가 1965년 가격보다 훨씬 높을 가능성이 높음을 의미하며, 따라서 99% 하락이 발생했을 때 훨씬 더 큰 타격을 입게 됩니다.
- 긴 보유 기간 (Long holding period): 1965년 이후 61년이 흘렀습니다. 대부분의 투자자는 매도해야 시점이 오기까지 이보다 훨씬 짧은 투자 지평을 가집니다. 은퇴를 위해 저축하는 젊은이들조차도 이에 해당합니다.
That said, I think we can all appreciate what this example teaches us about compound interest and the stock market's potential upside. Importantly, I hope this gets investors thinking about what it actually means to have to sell during a big market drawdown.
그럼에도 불구하고, 이 사례가 복리 이자와 주식 시장의 잠재적 상승 여력에 대해 무엇을 가르쳐주는지는 우리 모두 공감할 수 있을 것입니다. 중요하게는, 이 내용이 투자자들로 하여금 대규모 시장 하락 시기에 주식을 매도해야 한다는 것이 실제로 무엇을 의미하는지 깊이 생각해 보게 계기가 되기를 바랍니다.
Asymmetric upside affords you some downside 💪
In the stock market, the most you can lose is 100% of what you put in. Admittedly, 100% is a lot. On the other hand, some stocks go up by more than 100%. Some go up by 200%. Some go up by 2,000%. A few might even go up 591,000%. Of course, it’s extremely difficult to pick those stocks that go on to generate eye-popping returns. But you don’t have to do this to be a successful investor. A broadly diversified portfolio of stocks can also deliver far more upside than downside. S&P 500 index funds, which give you exposure to many high-performing stocks, have seen their value multiply over reasonable time horizons. Importantly, the S&P has a long history of rising much more than it falls.
주식 시장에서 손실을 볼 수 있는 최대 금액은 투자 원금의 100%입니다. 물론 100%라는 손실은 매우 큰 금액입니다. 반면에 어떤 주식은 100%를 초과하여 상승하기도 합니다. 200% 오르는 주식도 있고, 2,000% 오르는 주식도 있습니다. 심지어 어떤 주식은 591,000%까지 폭등하기도 합니다. 물론 이처럼 엄청난 수익률을 안겨줄 주식을 골라내기란 극도로 어렵습니다. 하지만 성공적인 투자자가 되기 위해 꼭 그런 주식을 찾아낼 필요는 없습니다. 광범위하게 분산 투자된 주식 포트폴리오 역시 하락 위험보다 훨씬 더 큰 상승 잠재력을 제공할 수 있습니다. 수많은 우량 주식에 분산 투자할 수 있는 S&P 500 인덱스 펀드의 경우, 합리적인 투자 기간 동안 가치가 몇 배로 불어나는 것을 목격해 왔습니다. 중요하게도, S&P 500은 하락할 때보다 훨씬 더 많이 상승해 온 오랜 역사를 가지고 있습니다.
Check out the chart below from Creative Planning's Charlie Bilello. It reviews the performance of history’s bull and bear markets. Since 1949, the average total return during bear markets was -31%. Meanwhile, the average total return during bull markets was +254%.
크리에이티브 플래닝(Creative Planning)의 찰리 빌렐로(Charlie Bilello)가 작성한 아래 차트를 살펴보세요. 이 차트는 역사적인 강세장과 약세장의 성과를 보여줍니다. 1949년 이후 약세장 동안의 평균 총수익률은 -31%였습니다. 반면 강세장 동안의 평균 총수익률은 +254%에 달했습니다.
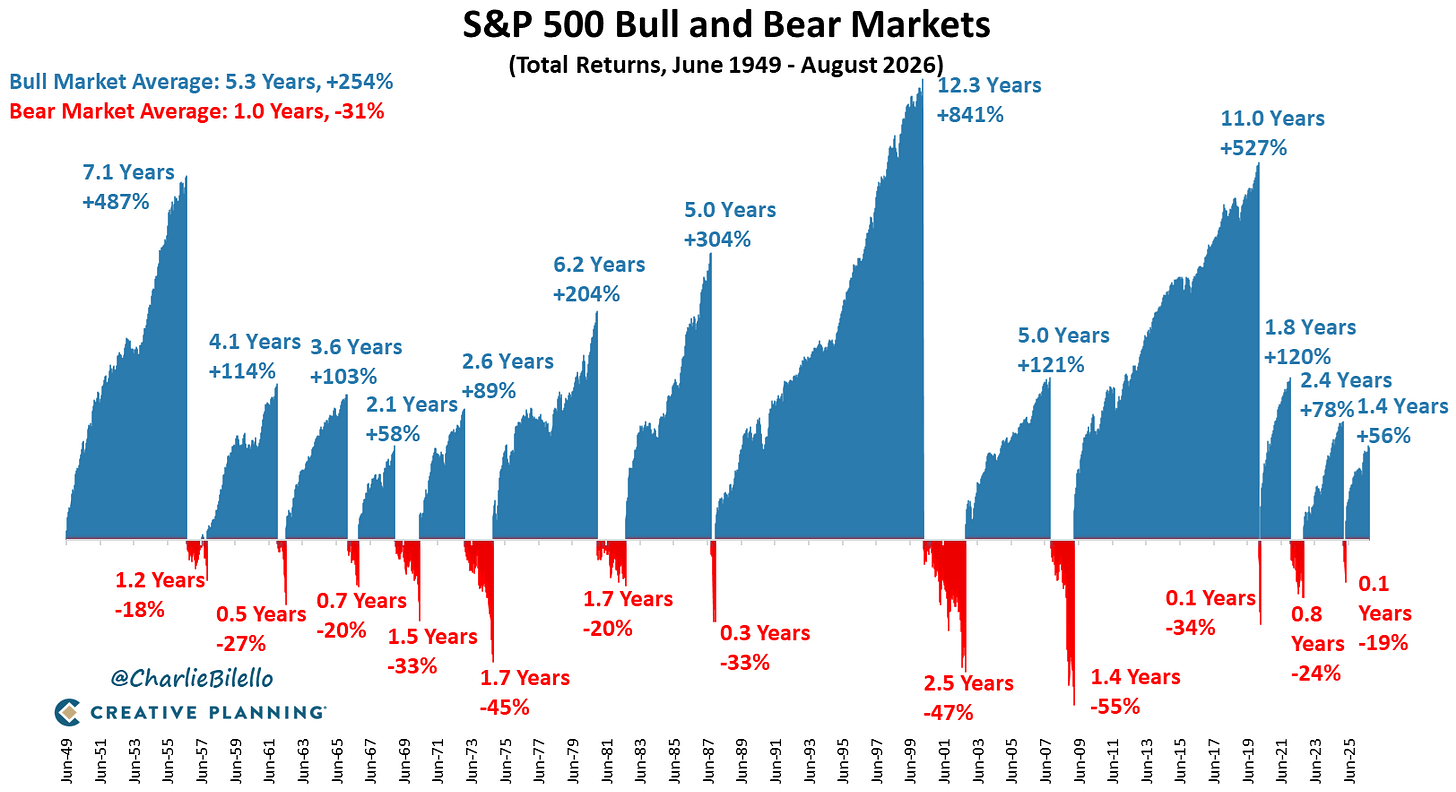
In other words, the value of an S&P index fund and its dividends more than triples in an average bull market. And these bull-market gains have always eclipsed and more than offset bear-market losses. This is probably obvious to anyone who’s seen a long-term chart of the stock market: essentially a line going up and to the right, with modest bumps along the way.
다시 말해, S&P 인덱스 펀드의 가치와 배당금은 평균적인 강세장 동안 세 배 이상 증가합니다. 그리고 이러한 강세장의 상승폭은 항상 약세장의 손실을 압도하며 이를 충분히 상쇄하고도 남았습니다. 이는 주식 시장의 장기 차트를 본 적이 있는 사람이라면 누구나 쉽게 알 수 있는 사실입니다. 주식 시장은 본질적으로 중간중간 완만한 충격이 있더라도 우상향하는 곡선이기 때문입니다.
A long-term diversified investor’s bear-case scenario 📉
Investors’ primary fear is losing money. What if there’s a bear market, and the value of my allocation to stocks falls 20%? Well, there’s a difference between being down 20% and being down 20%. If you bought stocks today and prices fell 20%, then you’d be down 20%. That’s unfortunate. It happens to the best of us. But what if you bought stocks about two years ago, experienced a 25% gain, and then the market fell 20%? You’d actually be at breakeven. Yes, you’d be down 20% from some higher value. But you wouldn’t have actually lost money based on the cost of your investment.
투자자들의 주된 두려움은 돈을 잃는 것입니다. 만약 약세장이 와서 주식에 투자한 자산의 가치가 20% 하락한다면 어떻게 될까요? 글쎄요, 20% 하락했다고 해서 다 같은 20% 하락은 아닙니다. 오늘 주식을 매수했는데 가격이 20% 하락했다면, 여러분의 자산은 20% 하락한 상태가 됩니다. 안타까운 일이지만, 누구에게나 일어날 수 있는 일입니다. 하지만 만약 지금으로부터 약 2년 전에 주식을 매수하여 25%의 수익을 경험한 뒤 시장이 20% 하락했다면 어떻게 될까요? 이 경우 여러분의 계좌는 실제로 본전(원금 수준)에 도달해 있을 것입니다. 그렇습니다, 더 높았던 고점 대비로는 20% 하락한 것이 맞습니다. 하지만 투자 원금과 비교했을 때 실제로 돈을 잃은 것은 아닙니다.
In a stock market that often falls but usually goes up, the odds that your portfolio is in the money — even in the midst of a bear market — improve as you extend your time horizon. Consider me. I started buying stocks for my retirement account in 2005 when the S&P 500 was around 1,200. Ever since, I’ve bought more periodically. Fast forward to today, when the S&P 500 is trading at 7,722. If the market fell 20%, that would send the S&P to 6,178, a level initially reached in mid-2025. The chart below marks this level with the dotted line.
종종 하락하더라도 대개는 상승하는 주식 시장에서는, 투자 기간을 늘릴수록 약세장 한복판에 있더라도 포트폴리오가 원금을 유지하고 있을(수익권에 있을) 확률이 높아집니다. 저를 예로 들어보겠습니다. 저는 S&P 500 지수가 1,200 부근이었던 2005년에 은퇴 계좌용 주식을 매수하기 시작했습니다. 그후로도 정기적으로 주식을 더 매수해 왔습니다. S&P 500 지수가 7,722에서 거래되고 있는 현재로 시계를 빨리 감아보겠습니다. 만약 시장이 20% 하락한다면, S&P 지수는 6,178까지 떨어지게 되는데, 이는 2025년 중반에 처음 도달했던 수준입니다. 아래 차트는 점선으로 이 수준을 표시하고 있습니다.
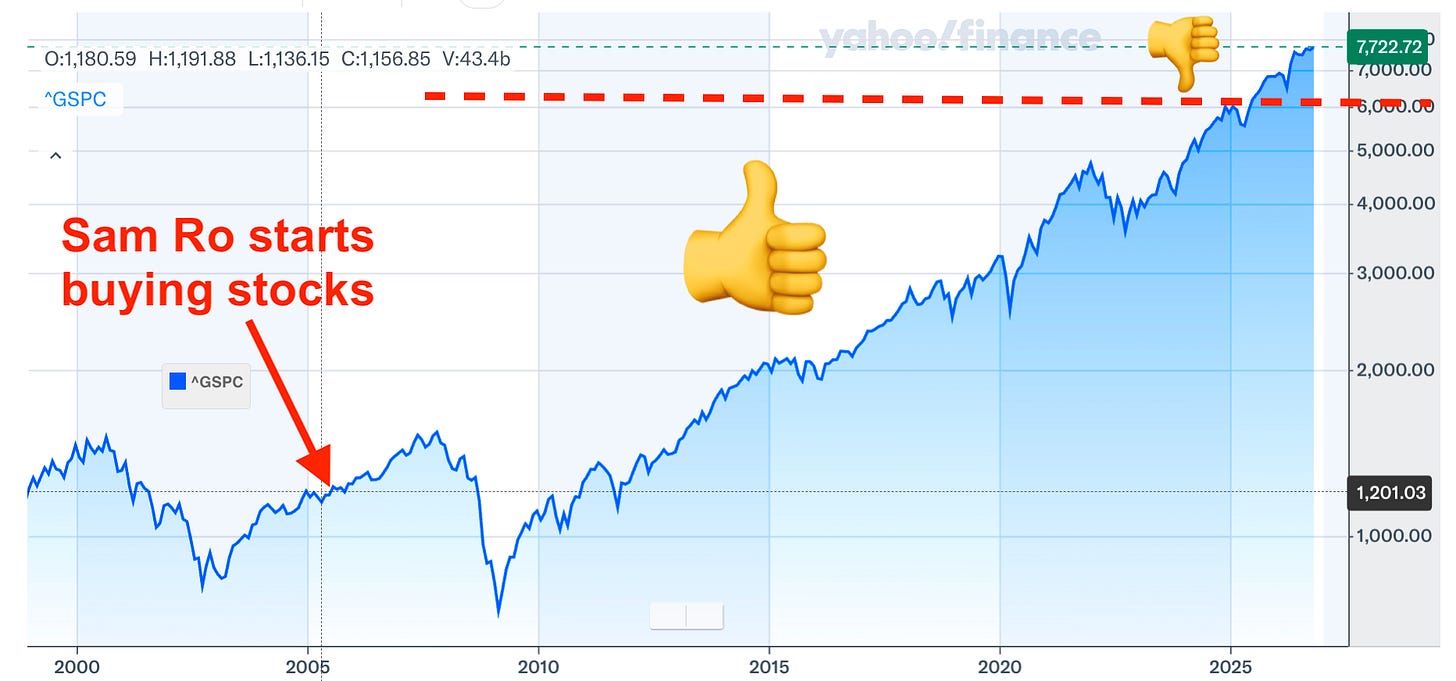
If the market fell 20% from current levels, then all of my purchases after mid-2025 (above the dotted line) would be in the red. But the bulk of my purchases were made over the 19 years before then (below the dotted line), when the market was much lower. That explains why, despite being down 20%, the value of my portfolio is considerably higher than the total of what I put in.
현재 수준에서 시장이 20% 하락하더라도, 2025년 중반 이후에 이루어진 모든 매수 건(점선 위)은 손실(마이너스)을 기록하게 될 것입니다. 하지만 저의 매수 물량 대부분은 그 이전 19년 동안(점선 아래) 시장이 훨씬 더 낮았던 시기에 이루어졌습니다. 이것이 바로 20% 하락을 겪더라도 제 포트폴리오의 가치가 총 투자 원금보다 훨씬 더 높은 이유를 설명해 줍니다.
The big picture 🖼️
It’s possible that when it’s time for you to sell, the market might be down more than 20%. But you’d have to be pretty unlucky, as the market has spent very little time in >20% drawdowns. Odds are market conditions will be much more favorable than that. Nevertheless, I think it’s helpful to understand what it really means for you and your portfolio when the market is off its high. Because if you’ve been investing for years, are you really down? Or are you up by a lot, but just not as much as you were?
막상 매도해야 할 시점이 되었을 때 시장이 20% 이상 하락해 있을 가능성도 있습니다. 하지만 시장이 20%를 초과하는 하락 폭을 기록하며 보낸 시간은 그리 길지 않기 때문에, 여러분이 그 상황에 처할 확률은 그리 높지 않습니다. 대개의 경우 시장 상황은 그보다 훨씬 더 유리할 것입니다. 그럼에도 불구하고, 시장이 고점에서 밀려났을 때 그것이 여러분과 여러분의 포트폴리오에 실제로 무엇을 의미하는지 이해하는 것은 큰 도움이 됩니다. 오랜 기간 동안 투자를 해왔다면, 여러분의 자산은 정말로 손실을 입은 것일까요? 아니면 여전히 큰 폭으로 수익을 내고 있는 상태이되, 다만 최고점일 때보다는 그 폭이 조금 줄어들었을 뿐인 것일까요?
-
Related from TKer:
- Does it always make sense to think of a 20% decline in your portfolio as a loss? 🤨
- The intimidating mathematical hurdle a beaten down stock market always clears 🙌
- Warren Buffett: ‘It takes just a few winners to work wonders’ 🏆
- Warren Buffett on luck and not beating yourself up over mistakes 🍀🤦🏻♂️
- The best investing wisdom shares a common theme 🧐
Review of the macro crosscurrents 🔀
📉The stock market declined last week, with the S&P 500 shedding 0.3% to end at 7,722.72. The index is now down 1.0% from its August 13 closing high of 7,798.99 and up 12.8% year-to-date. For market insights, check out the Stock Market tab at TKer. »
📉 지난주 주식 시장은 S&P 500 지수가 0.3% 하락하며 7,722.72로 마감했습니다. 이 지수는 8월 13일의 종가 기준 고점인 7,798.99 대비 1.0% 하락한 상태이며, 연초 이후 기준으로는 12.8% 상승한 상태입니다. 시장 인사이트에 대해서는 TKer의 주식 시장(Stock Market) 탭을 확인해 보세요. »
There were several notable data points and macroeconomic developments since our last review:
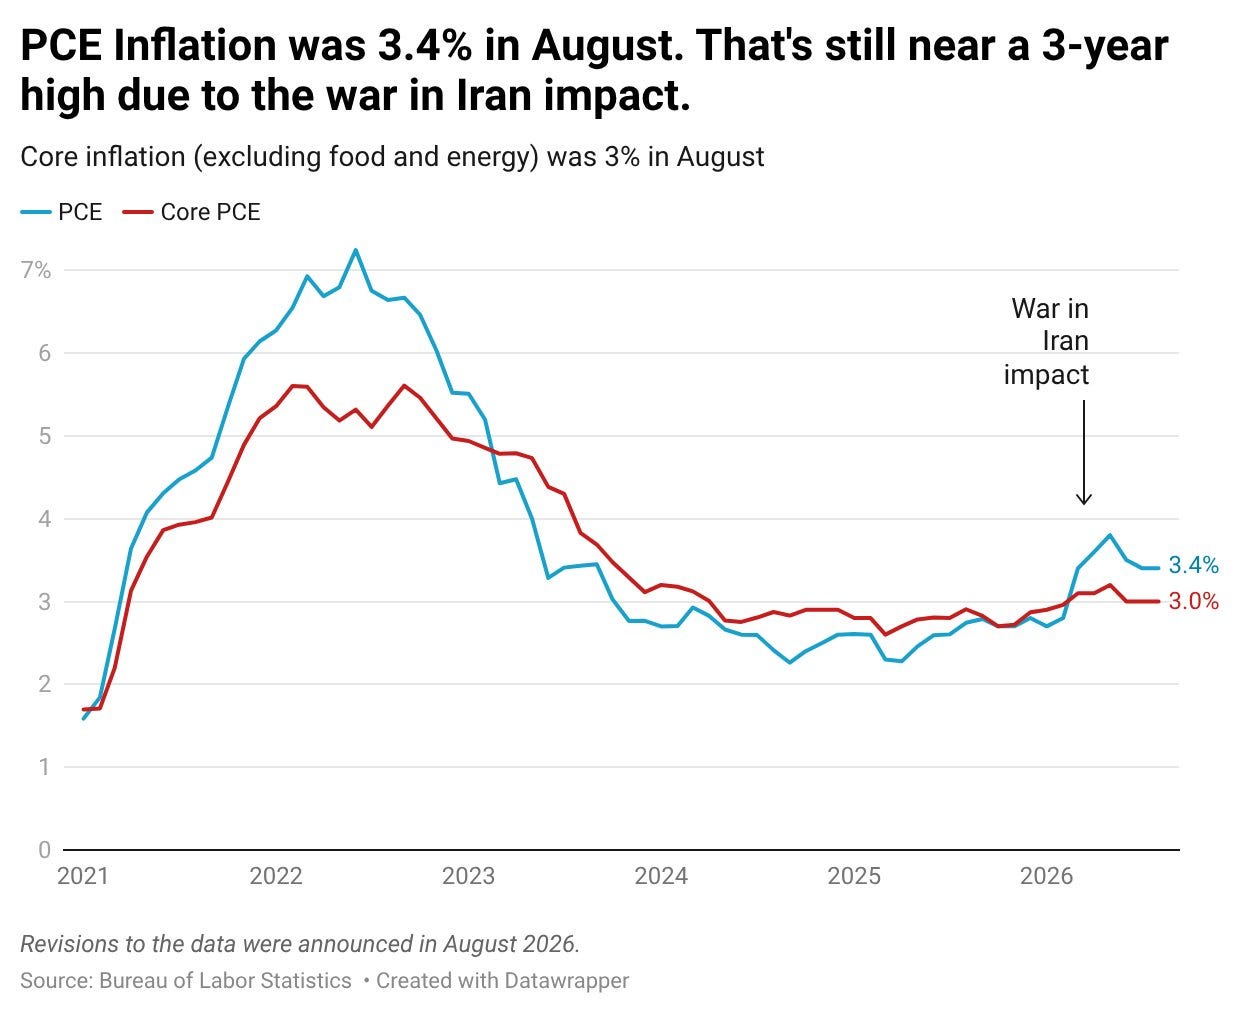
🎈 Fed’s preferred inflation measure cooled. The personal consumption expenditures (PCE) price index in August was up 3.4% from a year ago. The core PCE price index — the Federal Reserve’s preferred measure of inflation — was up 3.0% during the month, down from July’s 3.3% rate.
지난 리뷰 이후 주목할 만한 몇 가지 데이터 포인트와 거시경제적 발전 사항은 다음과 같습니다.
🎈 연준이 선호하는 인플레이션 지표가 둔화되었습니다. 8월 개인소비지출(PCE) 물가지수는 전년 동기 대비 3.4% 상승했습니다. 연방준비제도(Fed)가 선호하는 인플레이션 지표인 근원 PCE 물가지수는 해당 월 동안 3.0% 상승하여, 7월의 3.3% 상승률보다 낮아졌습니다.
On a month-over-month basis, the core PCE price index was up 0.2%. If you annualize the three-month trend in the monthly figures — a reflection of the short-term trend in prices — core PCE climbed 2.0%.
전월 대비 기준으로 근원 PCE 물가지수는 0.2% 상승했습니다. 월별 수치의 3개월 추세를 연율화해 보면—이는 물가의 단기적 추세를 반영하는 것입니다—근원 PCE는 2.0% 상승했습니다.
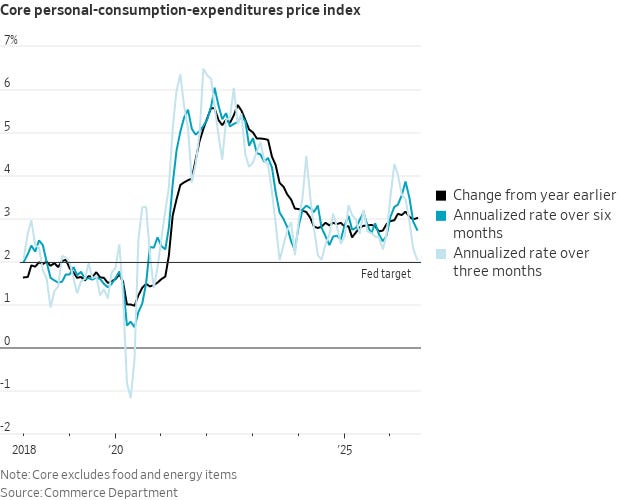
One month’s inflation print does not reflect a trend. But it’s encouraging to see at least one measure of inflation in line with the Federal Reserve’s 2% target. How price trends evolve in the near term continues to bear watching.
한 달 치 인플레이션 수치 하나가 곧 추세를 대변하는 것은 아닙니다. 하지만 인플레이션 지표 중 적어도 하나가 연방준비제도의 2% 목표치에 부합하는 모습을 확인한 것은 고무적인 일입니다. 향후 단기적으로 물가 추세가 어떻게 전개될지는 계속해서 주시할 필요가 있습니다.
For more on the Fed’s impact on markets, read: ‘When will the Fed cut rates?’ is not the right question for investors right now ✂️
연준이 시장에 미치는 영향에 대해 자세히 알아보려면 다음 글을 읽어보세요: '연준이 언제 금리를 인하할까?'는 지금 투자자들이 던져야 할 올바른 질문이 아닙니다 ✂️
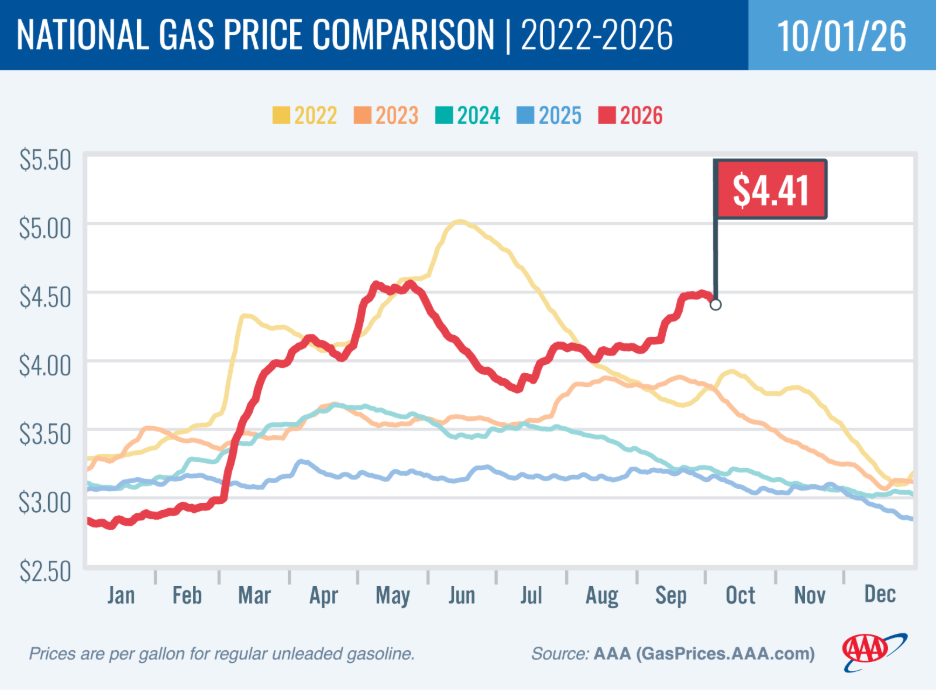
⛽️ Gas prices tick lower, but remain high. From AAA: “The national average for a gallon of regular gasoline dropped nearly 7 cents from last week to $4.41. This follows a record-setting September at the pump. The monthly average was $4.33, 50 cents higher than the previous September record of $3.83 set in 2023. Crude oil prices have dipped back into the $90 per barrel range, lowering the national average, but overall gas prices remain the highest they’ve ever been for this time of year.“
⛽️️ 휘발유 가격이 소폭 하락했으나 여전히 높은 수준을 유지하고 있습니다. 전미자동차협회(AAA)에 따르면: "일반 휘발유 1갤런의 전국 평균 가격은 지난주보다 약 7센트 하락한 $4.41를 기록했습니다. 이는 기록적인 9월 주유소 물가 상승에 이은 것입니다. 9월 월간 평균 가격은 $4.33로, 2023년에 기록했던 기존 9월 최고 기록인 $3.83보다 50센트 높았습니다. 원유 가격이 배럴당 90달러대 중반으로 다시 내려앉으면서 전국 평균 가격이 낮아지긴 했으나, 연중 이 시기 기준으로 전체 휘발유 가격은 역대 최고 수준을 유지하고 있습니다."
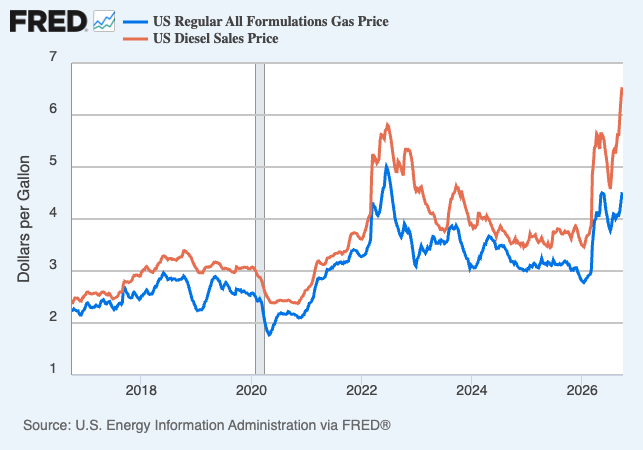
Here’s a longer-term look at the trajectory of gas and diesel prices, as tracked by the EIA.
미국 에너지정보청(EIA)이 집계한 휘발유 및 디젤 가격의 장기 추이를 살펴보면 다음과 같습니다.
For more on energy prices, read: Our love-hate relationship with rising oil prices in charts 💔🛢️📊
에너지 가격에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 차트로 보는 유가 상승에 대한 우리의 애증 관계 💔🛢️📊
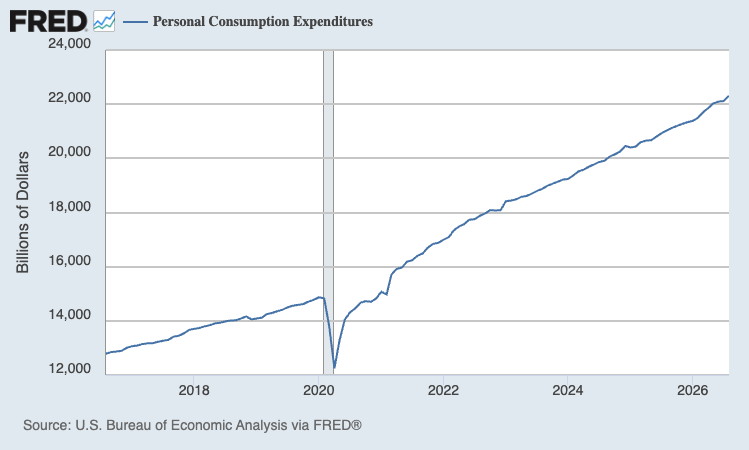
🛍️ Consumer spending ticks higher. According to BEA data, personal consumption expenditures increased 0.9% month-over-month in August to an annual rate of $22.3 trillion, an all-time high.
🛍️️ 소비자 지출이 소폭 증가했습니다. 미 상무부 경제분석국(BEA) 데이터에 따르면, 8월 개인소비지출(PCE)은 전월 대비 0.9% 증가하여 연환산 기준 22조 3,000억 달러로 사상 최고치를 기록했습니다.
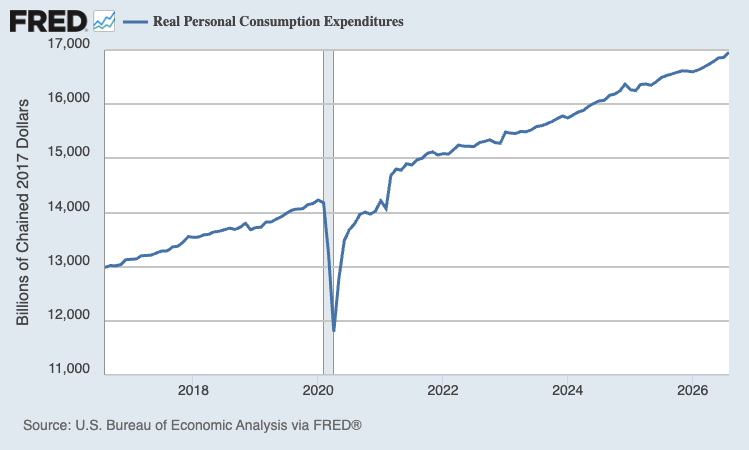
Adjusted for inflation, real personal consumption expenditures was unchanged from the prior month’s all-time high.
인플레이션을 감안한 실질 개인소비지출은 전월의 사상 최고치와 동일한 수준을 유지했습니다.
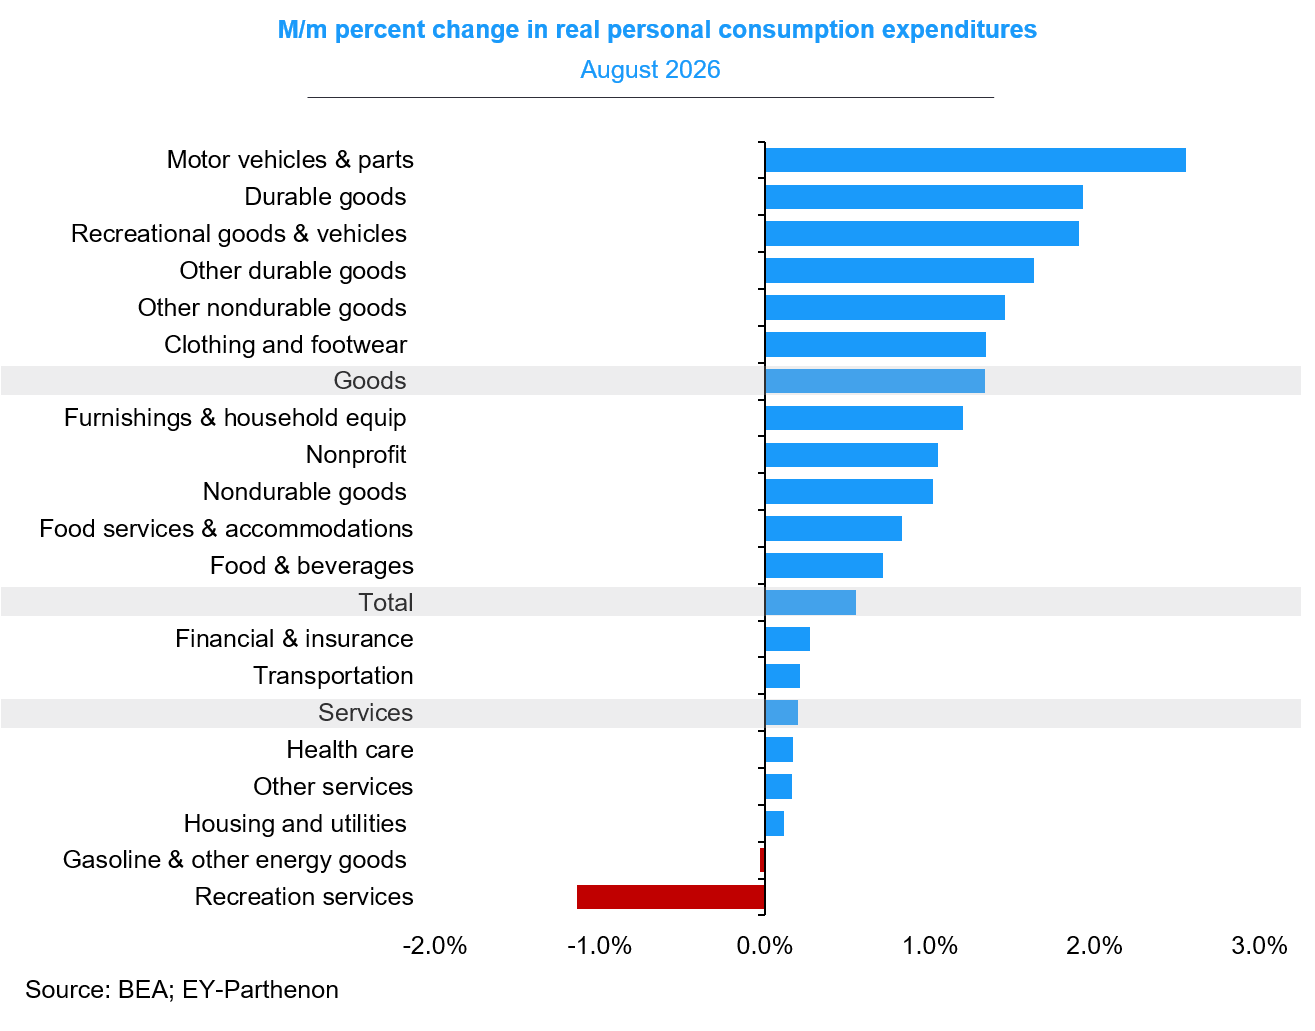
Here’s a breakdown of spending growth by category.
부문별 지출 증가 현황은 다음과 같습니다.
💰The personal saving rate is low, but that’s not obviously a bad sign. Personal saving — disposable personal income less personal consumption — has been shrinking over the past two years, causing the personal saving rate — personal saving as a percentage of disposable personal income — to trend lower. In August, the saving rate was 4.1%, its lowest level since Nov. 2022.
💰 개인 저축률이 낮지만, 그것이 곧바로 나쁜 신호를 의미하는 것은 아닙니다. 개인 저축(가처분 개인 소득에서 개인 소비를 뺀 금액)은 지난 2년 동안 감소해 왔으며, 이로 인해 개인 저축률(가처분 개인 소득 대비 개인 저축의 비율)은 하향세를 보이고 있습니다. 8월 저축률은 4.1%로 2022년 11월 이후 최저 수준을 기록했습니다.
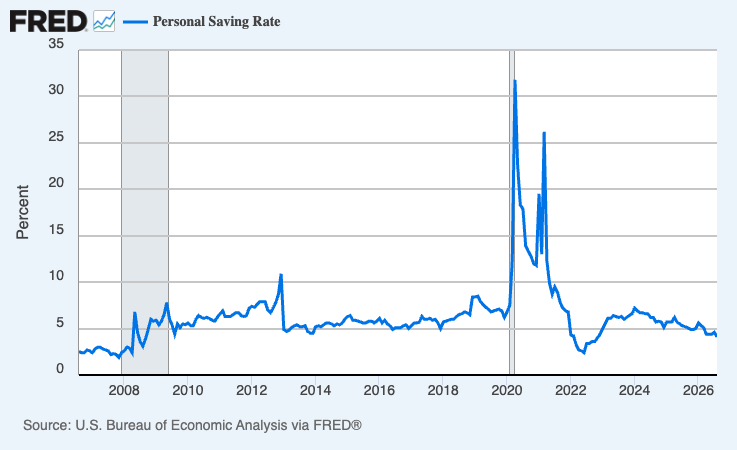
All else equal, this is not great. The implication is that more people are drawing from their savings to support their spending amid inflationary pressures. However, the saving rate tends to decline when net worths are rising. And net worths have been rising, driven by record-high home prices and elevated stock prices.
다른 조건이 동일하다면 이는 결코 좋은 현상이 아닙니다. 인플레이션 압박 속에서 지출을 충당하기 위해 더 많은 사람들이 저축을 헐어 쓰고 있음을 시사하기 때문입니다. 하지만 순자산이 증가할 때 저축률은 하락하는 경향이 있습니다. 그리고 사상 최고치를 경신 중인 주택 가격과 높은 수준의 주식 가격에 힘입어 순자산은 계속해서 증가해 왔습니다.
For more on this dynamic, read: A contrarian note about the falling personal saving rate 💸
이러한 역학관계에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 하락하는 개인 저축률에 대한 역발상적 노트 💸
💳 Card spending data is holding up. From BofA: “Total card spending per HH was up 5.6% y/y in the week ending Sep 26, according to BAC aggregated credit & debit card data. Relative to last week, y/y entertainment spending growth increased the most while furniture spending saw the largest decline. After a brief reversal last week, lower-income spending growth again outpaced higher-income in the week ending Sep 26.”
💳 카드 지출 데이터는 견조한 흐름을 유지하고 있습니다. 뱅크오브아메리카(BofA)에 따르면: "BAC의 집계된 신용 및 체크카드 데이터에 따르면, 9월 26일로 끝난 주의 가구당 총 카드 지출은 전년 동기 대비 5.6% 증가했습니다. 전주와 비교했을 때, 전년 대비 엔터테인먼트 지출 증가율이 가장 크게 상승한 반면 가구 지출은 가장 큰 폭의 감소세를 보였습니다. 지난주에 잠시 역전되었던 것과 달리, 9월 26일로 끝난 주에는 저소득층의 지출 증가율이 다시 고소득층의 지출 증가율을 상회했습니다."
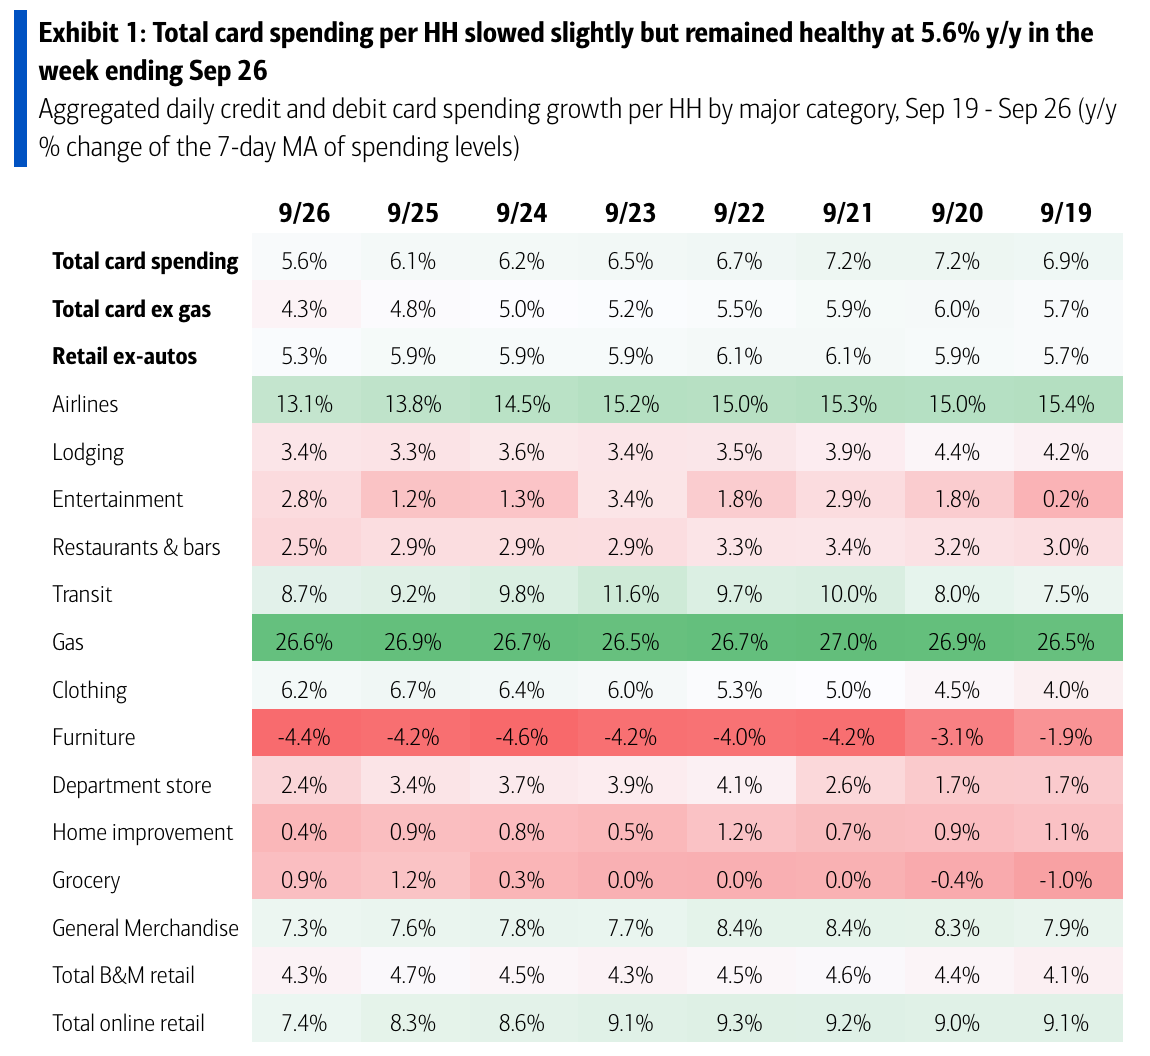
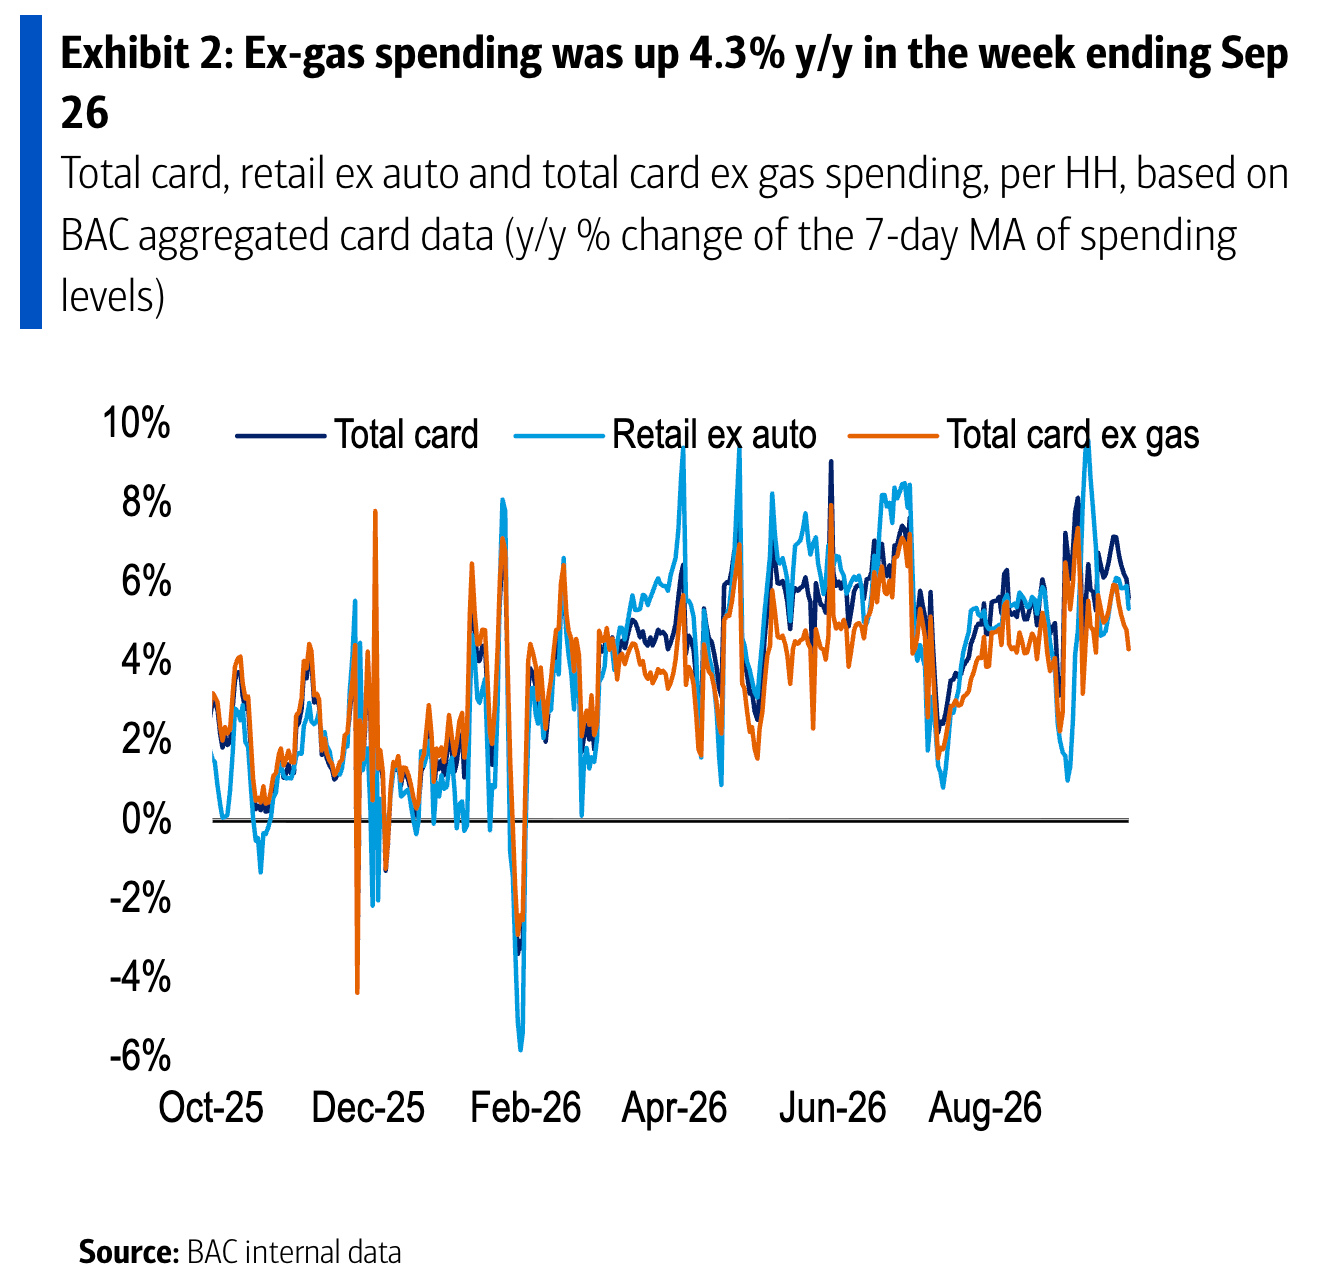
Consumer spending data has looked a lot better than consumer sentiment readings. For more on this contradiction, read: We’re taking that vacation whether we like it or not 🛫 and Household finances are both ‘worse’ and ‘good’ 🌦️
소비자 지출 데이터는 소비자 심리 지표에 비해 훨씬 더 양호한 모습을 보여주고 있습니다. 이러한 모순에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 원하든 원하지 않든 우리는 휴가를 떠납니다 🛫 및 가계 재정은 '악화'되는 동시에 '좋아지고' 있습니다 🌦️
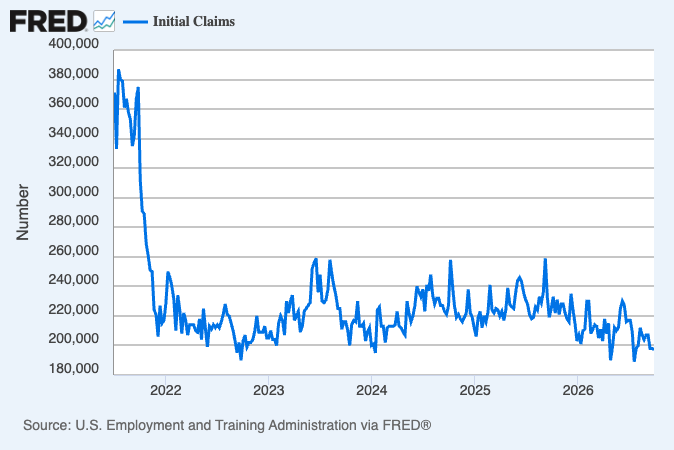
💼 New unemployment insurance claims, total ongoing claims remain low. Initial claims for unemployment benefits ticked down to 197,000 during the week ending Sept. 26, down from 198,000 the week prior. This metric remains at levels historically associated with economic growth.
💼 신규 실업보험 청구 건수 및 계속 실업수당 청구 건수가 낮은 수준을 유지하고 있습니다. 9월 26일로 끝난 주간의 신규 실업수당 청구 건수는 19만 7,000건으로 직전 주의 19만 8,000건에서 소폭 감소했습니다. 이 지표는 역사적으로 경제 성장을 나타내는 수준을 계속해서 유지하고 있습니다.
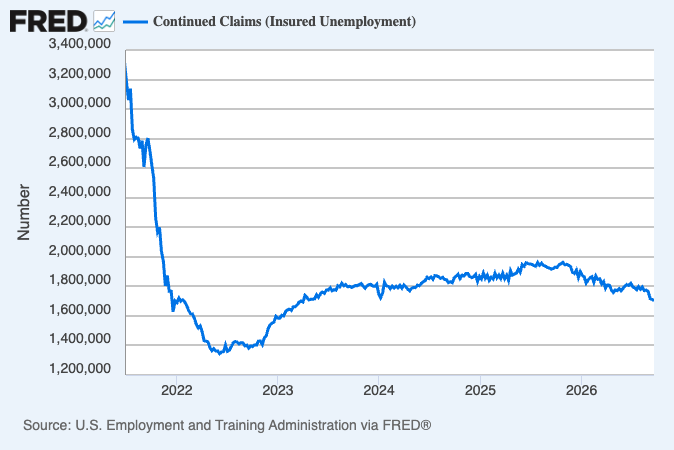
Insured unemployment, which captures those who continue to claim unemployment benefits, ticked down to 1.70 million during the week ending Sept. 19.
실업수당을 지속해서 수급하는 이들을 집계하는 계속 실업수당 청구 건수는 9월 19일로 끝난 주간에 170만 건으로 소폭 감소했습니다.
For more on the labor market, read: Why mass tech layoffs have little effect on total employment 💾
노동 시장에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 대규모 기술 기업 해고가 전체 고용에 미치는 영향이 미미한 이유 💾
💼 Jobs were created. According to the BLS’s Employment Situation report, U.S. employers added 29,000 jobs in September.
💼 일자리가 창출되었습니다. 미 노동통계국(BLS)의 고용동향 보고서에 따르면, 9월 미국의 고용주들은 2만 9,000개의 일자리를 추가했습니다.
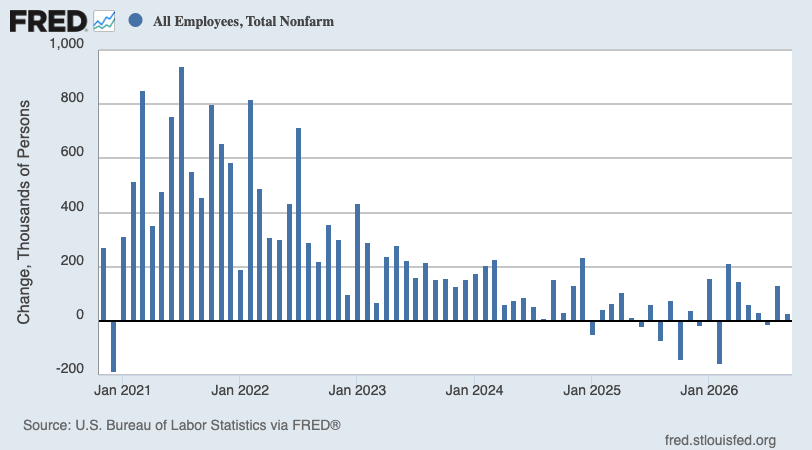
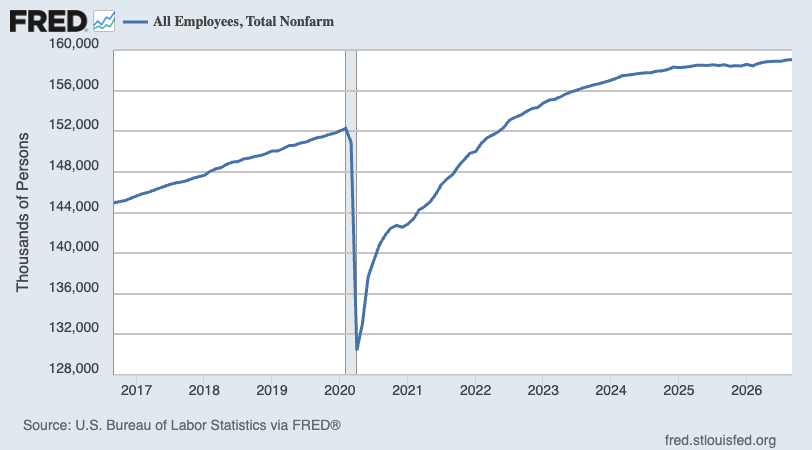
Total payroll employment rose to a record 159.04 million jobs in September.
총 급여 고용 인원은 9월에 1억 5,904만 개의 일자리로 사상 최고치를 기록했습니다.
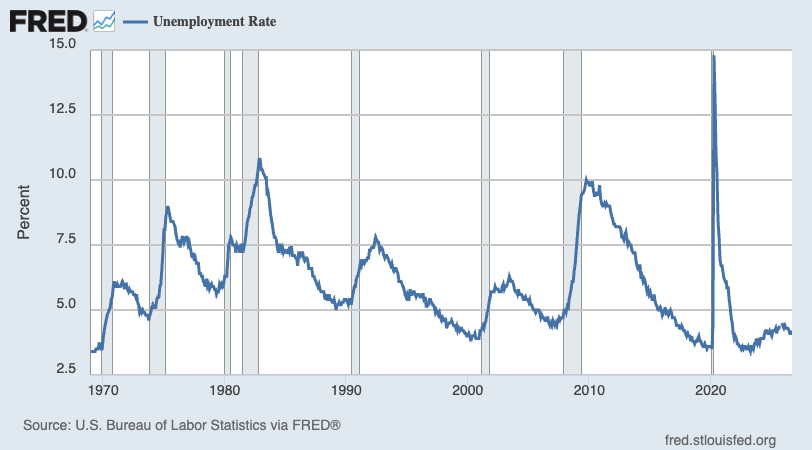
The unemployment rate — that is, the number of workers who identify as unemployed as a percentage of the civilian labor force — ticked up to 4.2% during the month. This was largely driven by entrants into the labor force.
실업률—즉, 실업자로 분류된 노동자들이 전체 민간 노동력에서 차지하는 비율—은 해당 월 동안 4.2%로 소폭 상승했습니다. 이는 주로 노동 시장에 새로 진입한 이들이 늘어난 데 기인합니다.
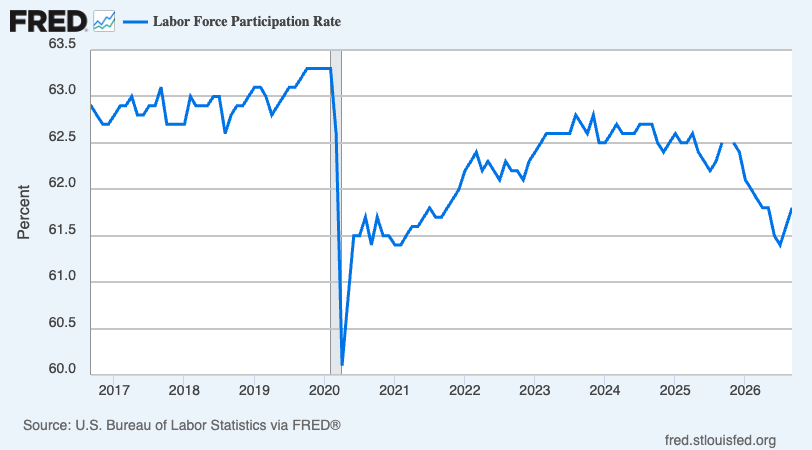
The labor force participation rate — that is, the number of employed and unemployed job seekers as a percentage of the civilian population — ticked up to 61.8% as 485,000 people entered the labor force.
노동참가율—즉, 취업자와 실업 상태의 구직자가 민간 인구에서 차지하는 비율—은 48만 5,000명이 노동 시장에 유입됨에 따라 61.8%로 소폭 상승했습니다.
The labor market is in decent shape, but clearly isn’t as hot as it was just a few years ago.
노동 시장은 양호한 상태를 유지하고 있지만, 불과 몇 년 전만큼 과열되어 있지는 않습니다.
For more on the labor market, read: Things are looking up in the labor market 👍
노동 시장에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 노동 시장이 호조를 보이고 있습니다 👍
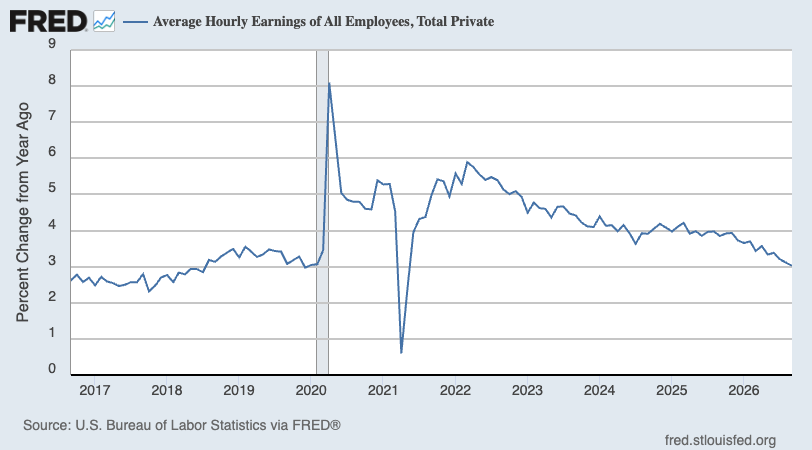
💸 Wage growth is cooling. Average hourly earnings rose by 0.1% month-over-month in September. On a year-over-year basis, September’s wages were up 3.0%.
💸 임금 상승세가 둔화되고 있습니다. 9월 평균 시간당 임금은 전월 대비 0.1% 상승했습니다. 전년 동기 대비로는 9월 임금이 3.0% 상승했습니다.
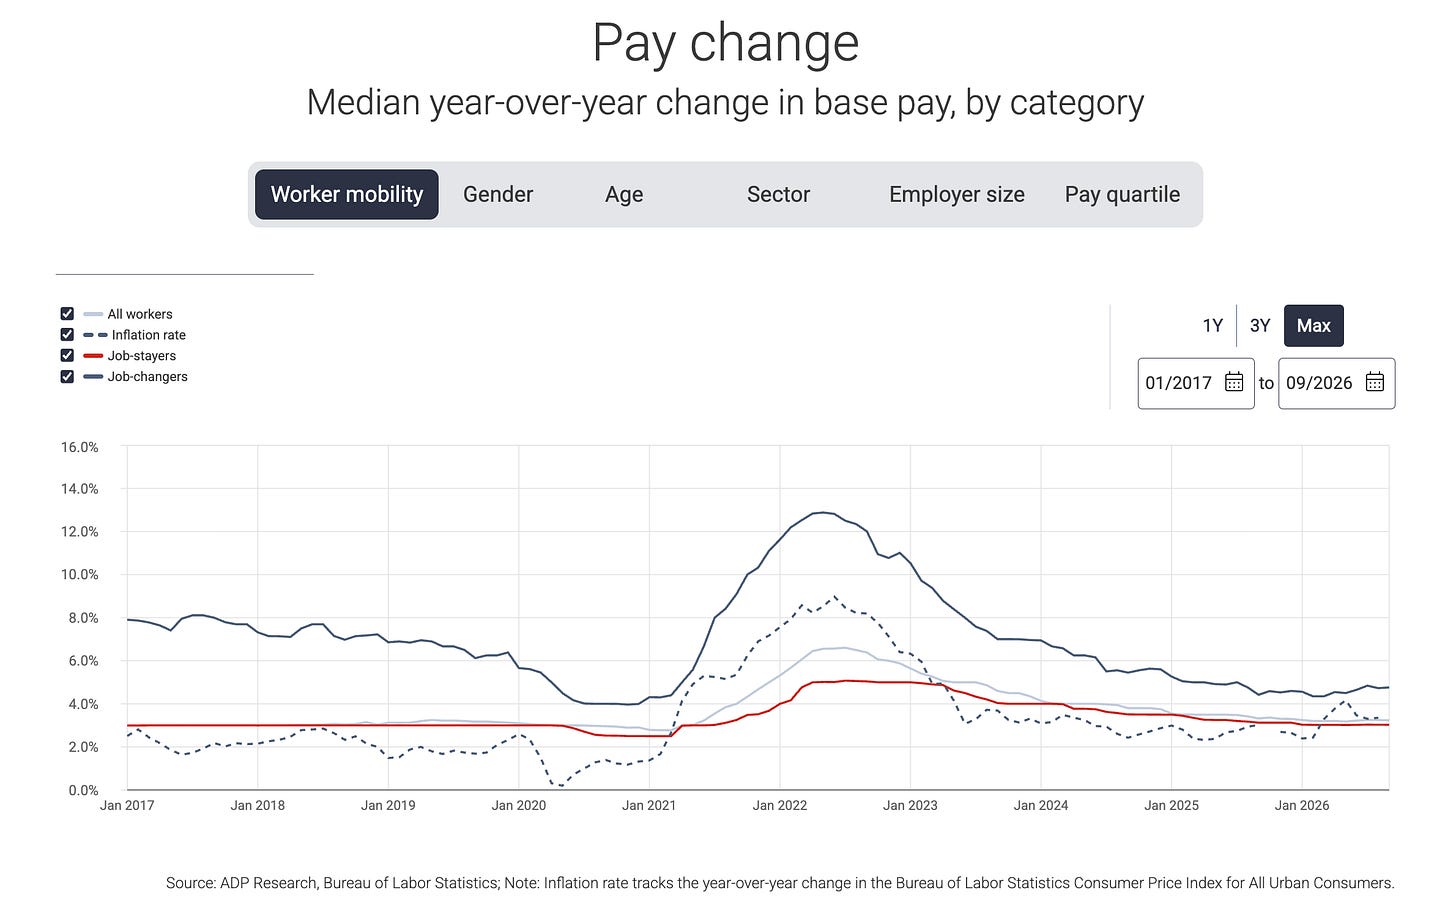
💰 Job switchers still get better pay. According to ADP, annual pay in September for people who changed jobs was up 4.8% from a year ago. That better-pay gap has been widening a bit in recent months. For those who stayed at their job, pay was up 3.0%, about what it’s been for the past year.
💰 이직자는 여전히 더 나은 급여를 받고 있습니다. ADP에 따르면, 9월 이직자들의 연간 임금은 전년 동기 대비 4.8% 상승했습니다. 이러한 임금 격차 우위 현상은 최근 몇 달 동안 다소 확대되었습니다. 한 직장에 계속 근무한 근로자들의 임금은 지난 1년 동안과 비슷한 수준인 3.0% 상승하는 데 그쳤습니다.
For more on why policymakers are watching wage growth, read: Revisiting the key chart to watch amid the Fed’s war on inflation 📈
정책 입안자들이 임금 상승세를 예의 주시하는 이유에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 연준의 인플레이션과의 전쟁 속에서 주목해야 할 핵심 차트 다시 보기 📈
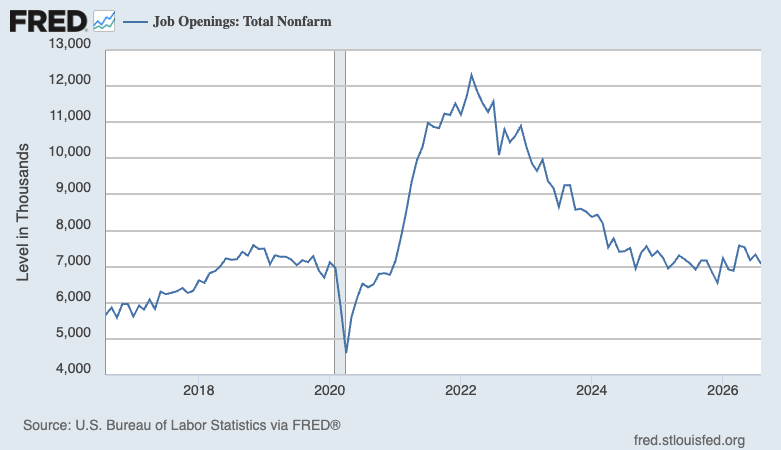
💼 Job openings declined. According to the BLS’s Job Openings and Labor Turnover Survey, employers had 7.08 million job openings in August, down from 7.34 million in July.
💼 구인 건수가 감소했습니다. 미 노동통계국(BLS)의 구인·이직 보고서(JOLTS)에 따르면, 8월 고용주들의 구인 건수는 708만 건으로 7월의 734만 건에서 감소했습니다.
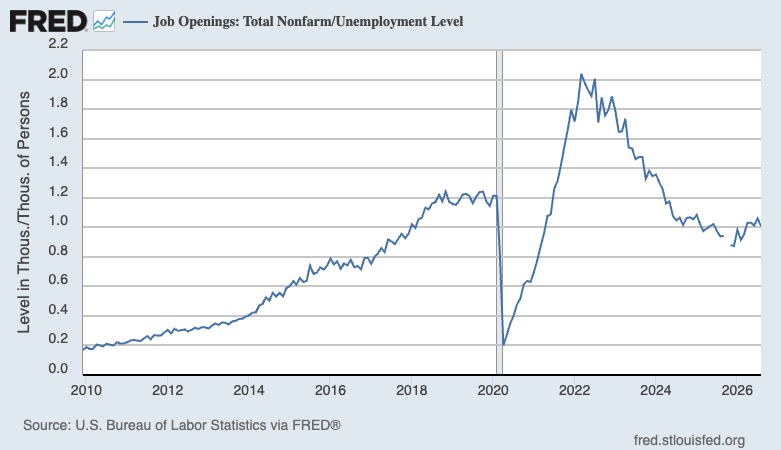
During the month, 7.03 million people were unemployed — meaning there were 1.0 job openings per unemployed person. This remains one of the most straightforward indicators of labor demand. However, this metric has returned to prepandemic levels.
해당 월 동안 실업자 수는 703만 명으로, 실업자 한 명당 구인 건수는 1.0개를 기록했습니다. 이는 노동 수요를 보여주는 가장 직관적인 지표 중 하나입니다. 다만, 이 지표는 팬데믹 이전 수준으로 복귀했습니다.
For more on job openings, read: Were there really twice as many job openings as unemployed people? 🤨
구인 건수에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 구인 건수가 실업자 수보다 정말 두 배나 많았을까요? 🤨
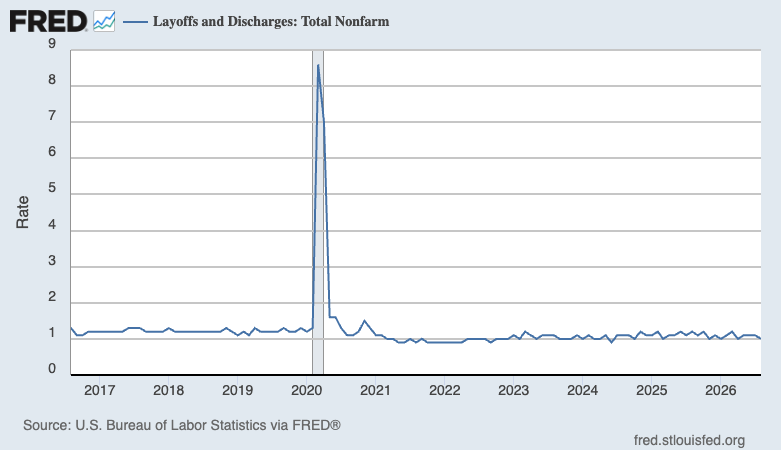
👍 Layoffs remain depressed, hiring remains firm. Employers laid off 1.64 million people in August. While challenging for the people affected, this figure represents just 1.0% of total employment. This metric remains slightly below prepandemic levels.
👍 해고는 낮은 수준을 유지하고 있으며, 채용은 견조하게 이어지고 있습니다. 8월 한 달 동안 고용주들은 164만 명을 해고했습니다. 해당 인원들에게는 힘든 일이겠지만, 이 수치는 전체 고용의 단 1.0%에 불과합니다. 이 지표는 팬데믹 이전 수준을 약간 밑도는 수준을 지속해서 유지하고 있습니다.
For more on layoffs, read: Mathematical context can totally change the story 🧮
해고에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 수학적 맥락은 완전히 이야기를 바꿀 수 있습니다 🧮
Hiring activity remains well above layoff activity. During the month, employers hired 5.19 million people.
채용 활동은 여전히 해고 활동을 큰 폭으로 상회하고 있습니다. 해당 월 동안 고용주들은 519만 명을 채용했습니다.
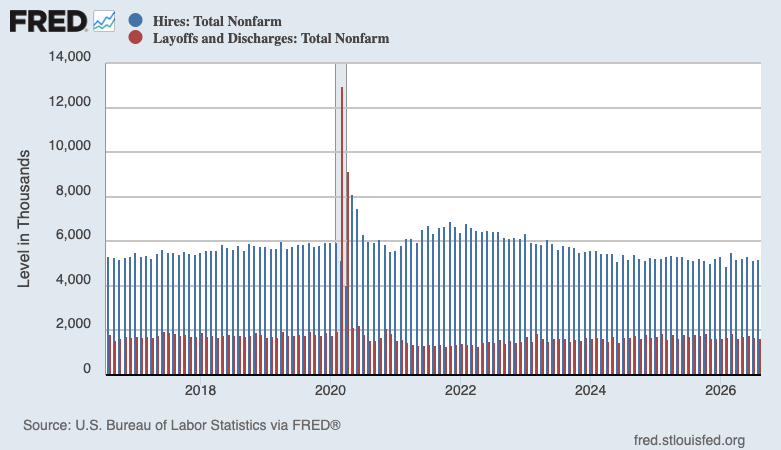
That said, the hiring rate — the number of hires as a percentage of the employed workforce — is relatively low, which could signal trouble ahead in the labor market.
그렇지만 고용된 노동자 대비 채용 건수의 비율인 채용률은 상대적으로 낮은 수준을 보이고 있으며, 이는 향후 노동 시장에 문제가 생길 수 있음을 암시할 수 있습니다.
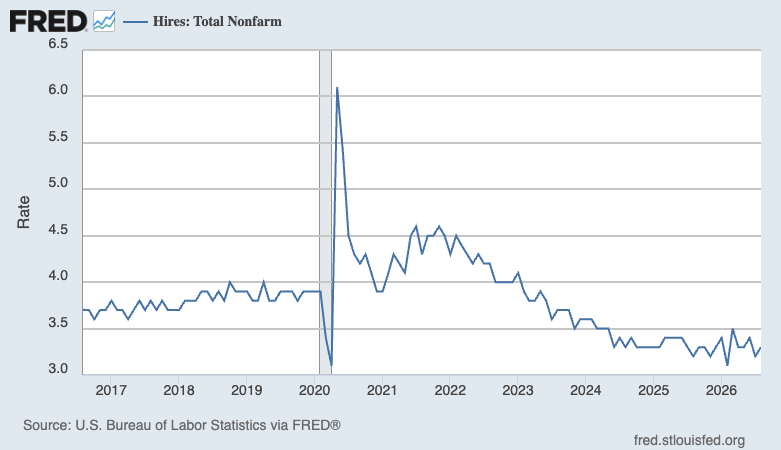
For more on why this metric matters, read: The hiring situation 🧩
이 지표가 중요한 이유에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 채용 상황 🧩
🤔 People are quitting less. In August, 3.07 million workers quit their jobs. This represents 1.9% of the workforce. The rate continues to trend below prepandemic levels.
🤔 사람들이 자발적 퇴사(quits)를 줄이고 있습니다. 8월 한 달 동안 307만 명의 근로자가 스스로 직장을 그만두었습니다. 이는 전체 노동력의 1.9%에 해당하는 수치이며, 이 퇴사율은 팬데믹 이전 수준을 밑도는 하향세를 계속해서 보이고 있습니다.
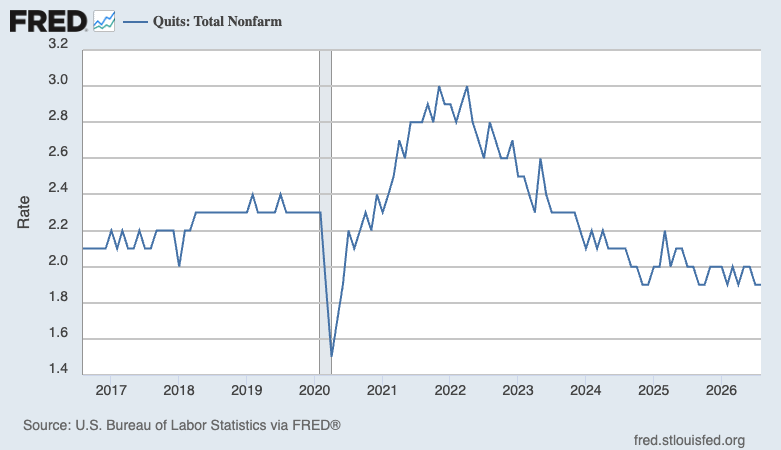
A low quits rate could mean a number of things: more people are satisfied with their job, workers have fewer outside job opportunities, wage growth is cooling, or productivity will improve as fewer people are entering new, unfamiliar roles.
낮은 퇴사율은 여러 가지 의미로 해석될 수 있습니다. 현재 직장에 만족하는 사람들이 늘어났거나, 외부에서 마땅한 일자리 기회를 찾기 어려워졌거나, 임금 상승세가 둔화되었거나, 혹은 새롭고 낯선 업무에 적응하는 인원이 줄어들면서 생산성이 향상될 수 있다는 점 등이 있습니다.
For more on this dynamic, read: The crummy labor market is yielding a ‘tenure dividend’ for corporations 💰
퇴사율의 이러한 역학 관계에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 부실한 노동 시장이 기업들에게 '근속 배당금'을 안겨주고 있습니다 💰
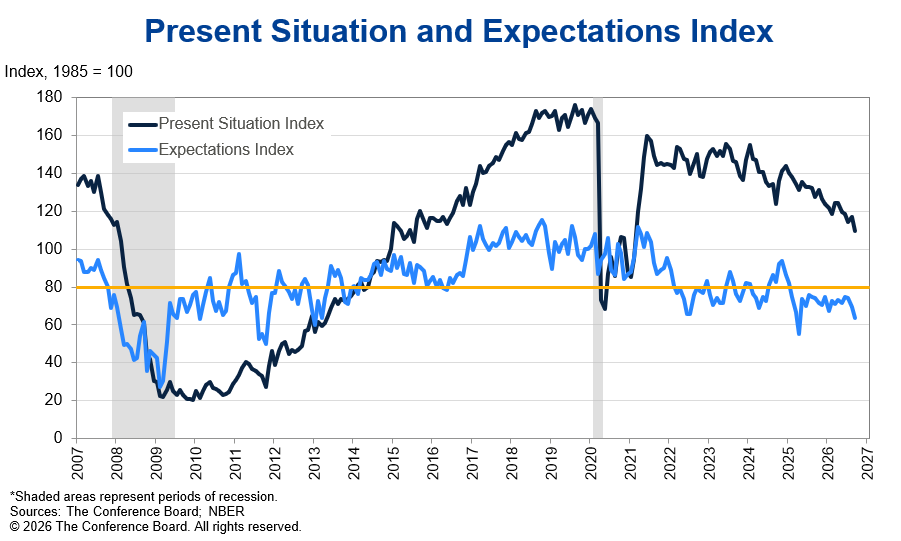
👎 Consumer vibes tumbled. The Conference Board’s Consumer Confidence Index fell by 6.7 points in September. From the report: “The Present Situation Index fell sharply, while the Expectations Index slipped further into negative territory. Consumer appraisals of current business conditions became negative for the first time since September 2024. Perceptions of the current labor market also worsened, though remained within positive territory. Over the next six months, consumers expected both business conditions and the labor market to weaken. Consumers still anticipated their household incomes to rise, but less so compared to previous months.”
👎 소비자 심리가 급락했습니다. 콘퍼런스보드(The Conference Board)의 소비자신뢰지수(Consumer Confidence Index)는 9월에 6.7포인트 하락했습니다. 보고서 내용은 다음과 같습니다: "현재상황지수(Present Situation Index)가 급격히 하락했으며, 기대지수(Expectations Index)는 마이너스 영역으로 더욱 미끄러졌습니다. 현재 경기 상황에 대한 소비자들의 평가는 2024년 9월 이후 처음으로 부정적으로 돌아섰습니다. 현재 노동 시장에 대한 인식 역시 악화되었으나 여전히 플러스 영역에는 머물렀습니다. 향후 6개월 동안 소비자들은 경기 상황과 노동 시장 모두 약화될 것으로 예상했습니다. 가계 소득이 증가할 것이라는 기대는 여전히 유지되었지만, 이전 달들에 비해서는 그 폭이 줄어들었습니다."
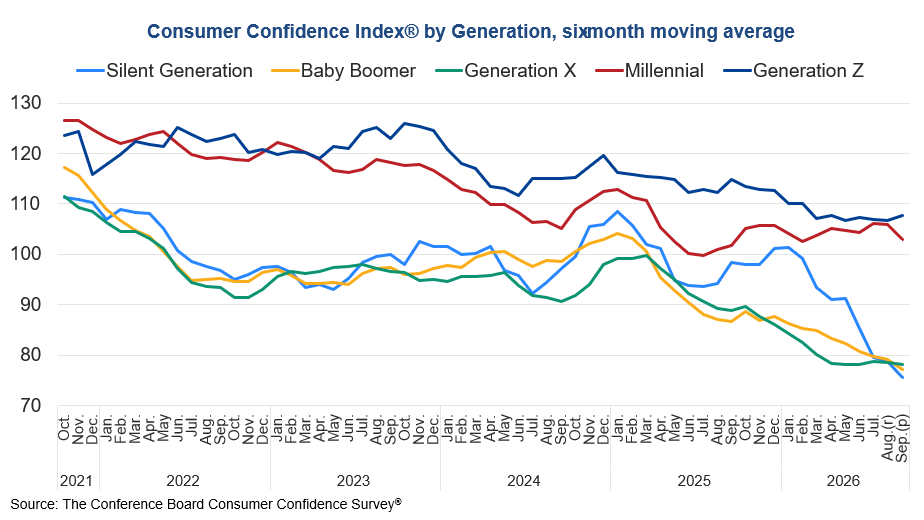
More from the report: “On a six-month moving average basis, confidence across all age groups and nearly all income groups trended downward. While higher-income groups remained generally more optimistic, those with a household income of $125,000-$149,000 reported the greatest decline in confidence over the last six months. By generation, confidence for Gen Z, followed by Millennials, remained the highest on a six-month moving average basis. Confidence among the three oldest generations—Generation X, Baby Boomers, and the Silent Generation—continued to weaken. Confidence fell in September across all political affiliations—Democrats, Republicans, and Independents.”
보고서의 추가 내용은 다음과 같습니다: "6개월 이동평균 기준을 살펴보면, 모든 연령대와 거의 모든 소득 계층에서 소비자 심리가 하향 곡선을 그렸습니다. 고소득층은 대체로 낙관적인 태도를 유지했으나, 연 소득 12만 5,000달러~14만 9,000달러 사이의 계층에서 지난 6개월 동안 가장 큰 폭의 신뢰도 하락이 관측되었습니다. 세대별로는 Z세대의 신뢰도가 가장 높았고 밀레니얼 세대가 그 뒤를 이었습니다. 반면 가장 연령대가 높은 세대인 X세대, 베이비부머, 그리고 침묵의 세대의 신뢰도는 계속해서 약화되었습니다. 민주당, 공화당, 무소속 등 모든 정치적 성향에 걸쳐 9월 소비자 심리가 하락했습니다."
For more on consumer sentiment, read: What consumers do > what consumers say 🙊 and The economy may not be working for everyone right now, but it’s at least working for stock market investors 🎭
소비자 심리에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 소비자가 하는 행동 > 소비자가 하는 말 🙊 및 현재 경제가 모든 사람에게 호조인 것은 아닐지라도, 적어도 주식 시장 투자자들에게는 작동하고 있습니다 🎭
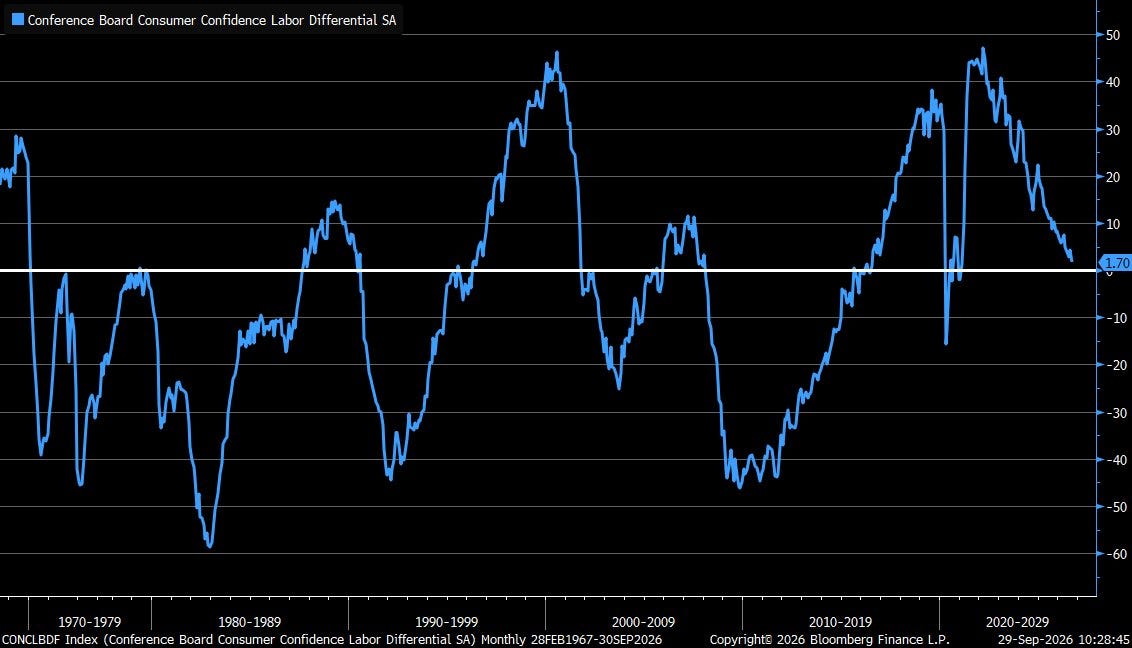
👎 Consumers feel worse about the labor market. From The Conference Board: “Consumers’ views of the labor market softened in September: 23.6% of consumers said jobs were ‘plentiful,’ down from 24.5% in August. 21.9% of consumers said jobs were ‘hard to get,’ up from 20.3%.”
👎 소비자들은 노동 시장에 대해 더 부정적인 인식을 갖게 되었습니다. 콘퍼런스보드(The Conference Board)에 따르면: "9월 소비자들의 노동 시장 평가는 약화되었습니다. 일자리가 '풍부하다'고 답한 소비자는 23.6%로 8월의 24.5%에서 하락했습니다. 반면 일자리를 '구하기 어렵다'고 답한 소비자는 21.9%로 8월의 20.3%에서 상승했습니다."
Many economists monitor the spread between these two percentages (a.k.a., the labor market differential). The direction of the spread reflects a cooling sentiment toward the labor market.
많은 경제학자들은 이 두 응답 비율의 격차(노동 시장 스프레드)를 모니터링합니다. 이 스프레드의 방향은 노동 시장에 대한 냉각된 심리를 그대로 반영합니다.
More from The Conference Board: “Consumers were also more negative about the labor market outlook in September: 14.0% of consumers expected more jobs to be available, down from 14.8% in August. 28.4% expected fewer jobs, up from 26.1%.“
콘퍼런스보드의 추가 내용입니다: "9월 소비자들은 노동 시장 전망에 대해서도 더욱 부정적인 입장을 보였습니다. 향후 일자리가 더 늘어날 것으로 예상한 소비자는 14.0%로 8월의 14.8%에서 하락했습니다. 반면 일자리가 더 줄어들 것으로 예상한 소비자는 28.4%로 26.1%에서 상승했습니다."
For more on the labor market, read: Things are looking up in the labor market 👍
노동 시장에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 노동 시장이 호조를 보이고 있습니다 👍
🏠 Mortgage rates rise. According to Freddie Mac, the average 30-year fixed-rate mortgage rose to 7.28%, up from 7.03% last week. This is the highest average rate since Nov. 2023.
🏠 모기지 금리가 상승했습니다. 프레디맥(Freddie Mac)에 따르면, 평균 30년 고정 모기지 금리가 지난주 7.03%에서 7.28%로 상승했습니다. 이는 2023년 11월 이후 가장 높은 평균 금리입니다.
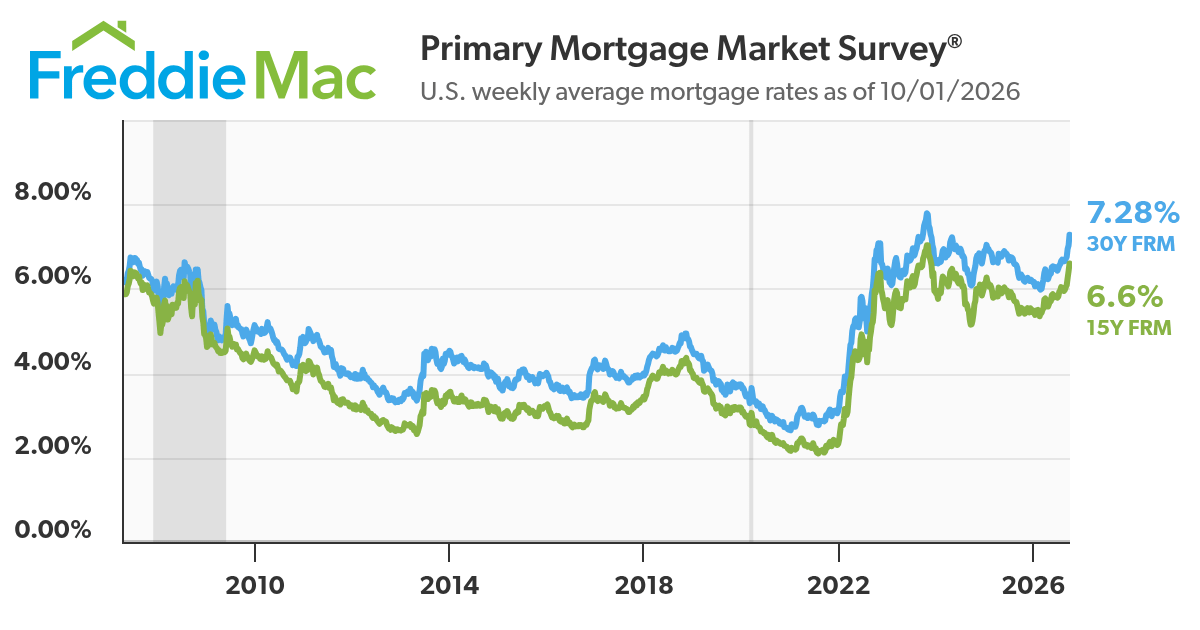
As of Q2, there were 149.5 million housing units in the U.S., of which 87.0 million were owner-occupied and about 40% were mortgage-free. Of those carrying mortgage debt, almost all have fixed-rate mortgages, and most of those mortgages have rates that were locked in before rates surged from 2021 lows. All of this is to say: Most homeowners are not particularly sensitive to the weekly movements in home prices or mortgage rates.
올해 2분기 기준 미국의 주택 수는 1억 4,950만 채였으며, 이 중 8,700만 채가 자가 소유였고 약 40%는 모기지 부채가 전혀 없는 상태였습니다. 모기지 부채를 안고 있는 주택 소유자들 중 대다수는 고정금리 모기지를 이용하고 있으며, 이들 대부분은 금리가 2021년 저점 대비 급등하기 전에 낮은 금리로 고정해 둔 상태입니다. 이 모든 것이 의미하는 바는 다음과 같습니다: 대다수의 주택 소유자들은 주택 가격이나 모기지 금리의 주간 변동에 크게 민감하게 반응하지 않는다는 점입니다.
For more on mortgages and home prices, read: Why home prices and rents are creating all sorts of confusion about inflation 😖
모기지와 주택 가격에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 주택 가격과 임대료가 인플레이션에 관한 온갖 혼란을 야기하는 이유 😖
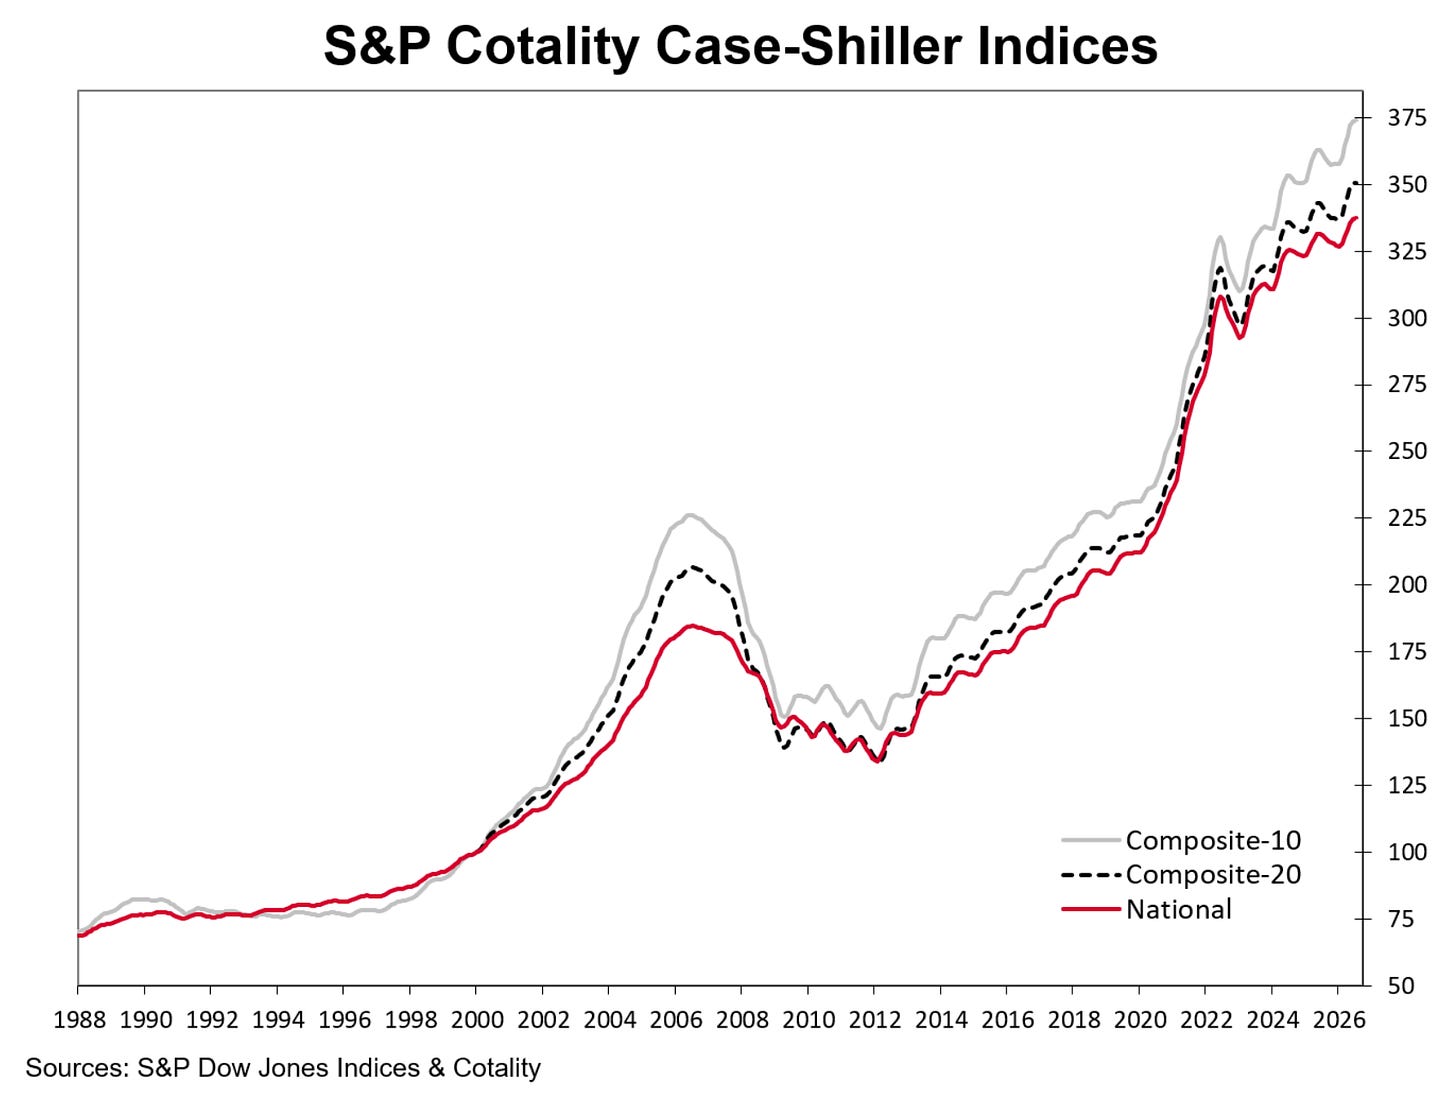
🏠 Home prices rose. According to the S&P CoreLogic Case-Shiller index, home prices were up 1.9% year-over-year in July and 1.6% month-over-month. From S&P Dow Jones Indices’ Rebecca Kaufman: “While home prices continued to decline in real terms in July 2026, marking the 14th consecutive month of real declines, slightly lower inflation and stronger nominal home price appreciation helped narrow the gap.”
🏠 주택 가격이 상승했습니다. S&P 코어로직 케이스-실러 지수에 따르면, 7월 주택 가격은 전년 동기 대비 1.9%, 전월 대비 1.6% 상승했습니다. S&P 다우존스 인덱스의 레베카 카프만(Rebecca Kaufman)은 다음과 같이 밝혔습니다: "2026년 7월 실질 기준으로 주택 가격이 계속 하락하며 14개월 연속 실질 하락세를 기록했지만, 물가 상승률이 소폭 낮아지고 명목 주택 가격 상승세가 강해지면서 격차가 좁혀졌습니다."
For more on how home prices and how they may be affecting the economy, read: A contrarian note about the falling personal saving rate...💸
주택 가격과 그것이 경제에 미칠 수 있는 영향에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 하락하는 개인 저축률에 대한 역발상적 노트...💸
📋 Manufacturing activity surveys signal growth, but also challenges. From S&P Global’s September U.S. Manufacturing PMI: “September has seen the pace of US manufacturing growth pick up a gear again, the PMI lifting to its highest since May 2022 as a surge in new orders encouraged factories to lift output sharply higher and take on workers in increasing numbers. Order book backlogs are rising and suppliers are increasingly busy, pointing to stretched capacity as companies struggle to meet demand across both consumer-facing and business sectors. This is most notable in the investment and production of machinery and equipment, linked in many cases to rising AI-related spend. Safety stock building amid price and supply chain worries also continues to support demand, though the ongoing loss of export orders remains a disappointment. While sending an encouraging signal for further growth of manufacturing capacity in the coming months, the indication that demand is outstripping supply also means inflationary pressures remain a key area of concern, especially amid high oil prices.”
📋 제조업 경기 설문조사는 성장을 시사하고 있지만, 동시에 도전 과제도 보여주고 있습니다. S&P 글로벌의 9월 미국 제조업 PMI에 따르면: "9월에는 미국 제조업의 성장 속도가 다시 한번 빨라졌습니다. 신규 주문 급증으로 공장들이 생산량을 크게 늘리고 고용을 확대하면서 PMI가 2022년 5월 이후 최고치로 상승했습니다. 수주 잔고가 증가하고 공급업체들이 점점 더 바빠짐에 따라, 소비재 및 기업용 부문 전반에서 기업들이 수요를 맞추기 위해 역량 한계에 부딪히고 있음을 보여줍니다. 이는 AI 관련 지출 증가와 맞물린 기계 및 장비의 투자와 생산에서 가장 두드러집니다. 가격 및 공급망 우려 속에서 안전 재고를 비축하는 움직임도 계속해서 수요를 뒷받침하고 있으나, 수출 주문의 지속적인 부진은 여전히 아쉬운 부분입니다. 향후 몇 달간 제조업 생산 능력이 더욱 성장할 것이라는 고무적인 신호를 보내는 한편, 수요가 공급을 앞지르고 있다는 표시는 인플레이션 압력이 여전히 주요 우려 사항임을 의미하며, 특히 높은 유가 속에서 더욱 그렇습니다."
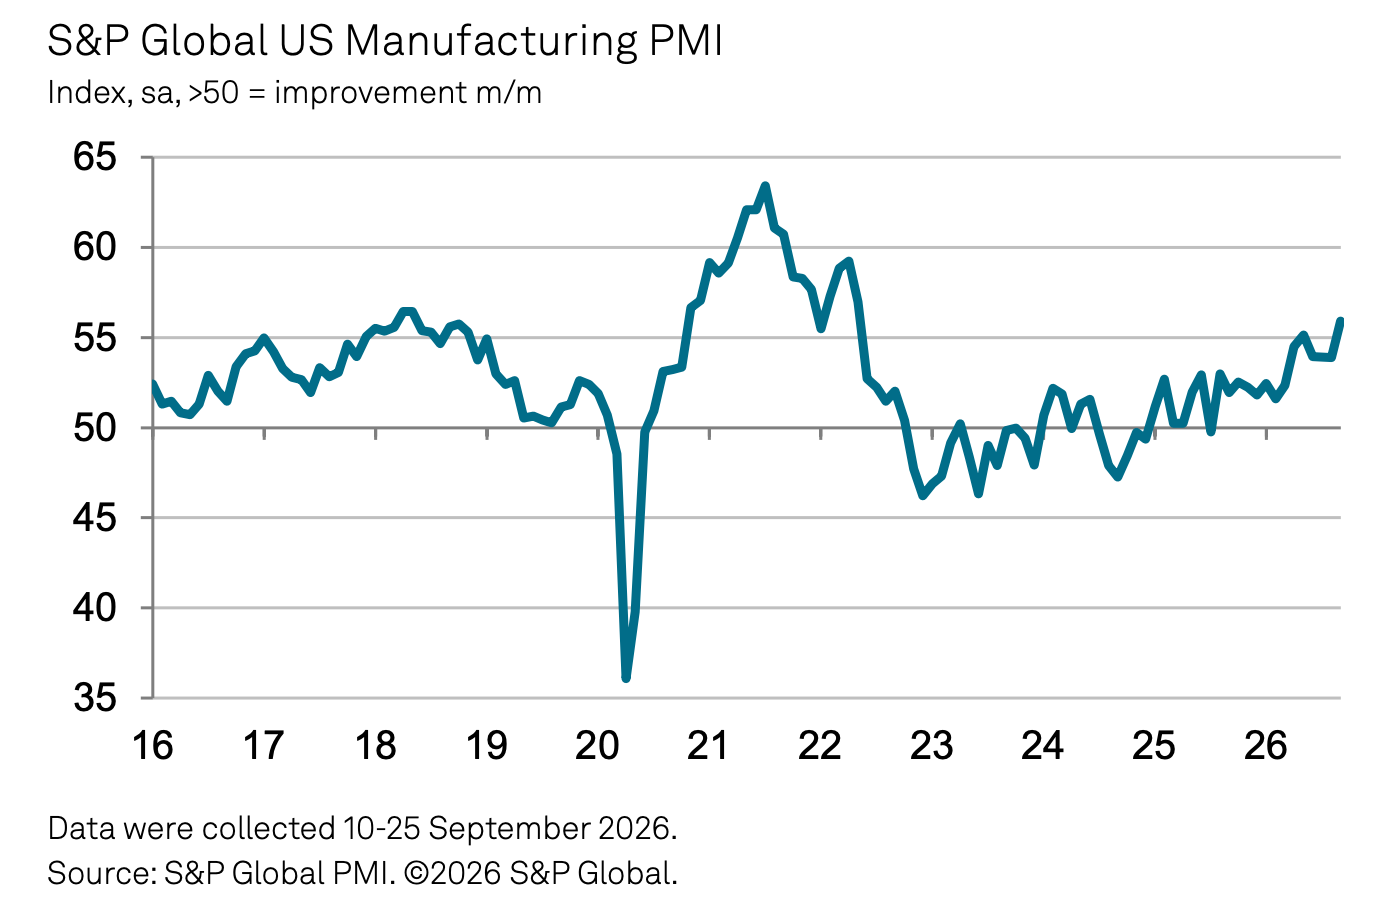
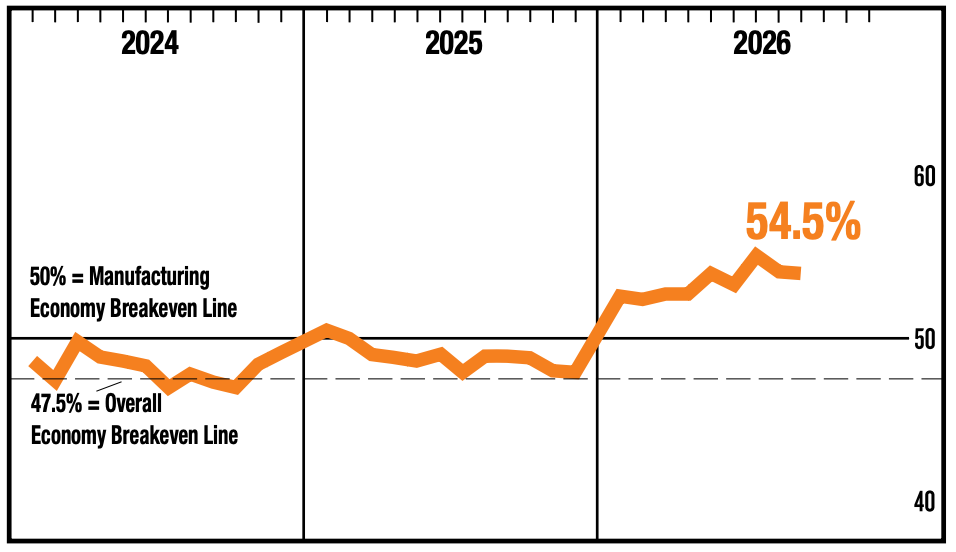
Similarly, the ISM September Manufacturing PMI signaled growth.
마찬가지로 ISM 9월 제조업 PMI도 성장을 시사했습니다.
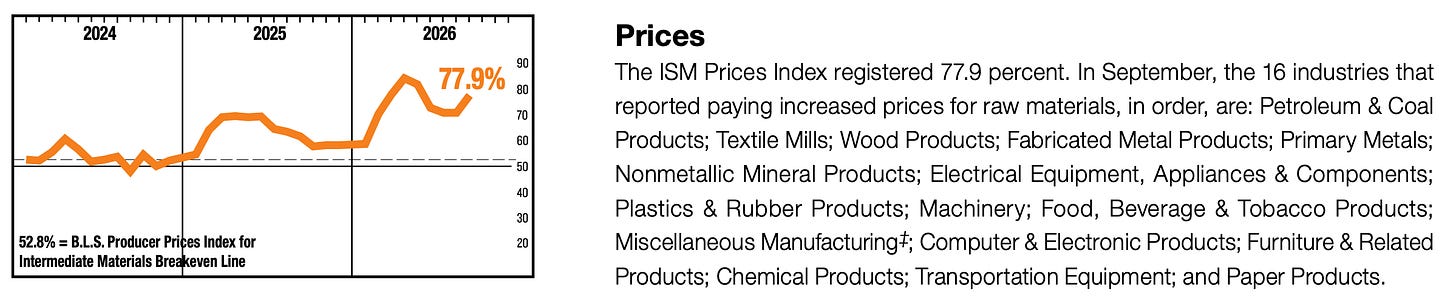
The ISM survey also signaled inflation.
ISM 설문조사 역시 인플레이션을 시사했습니다.
Keep in mind that during times of perceived stress, soft survey data tends to be more exaggerated than actual hard data.
체감되는 스트레스 상황에서는 부드러운 설문조사 데이터가 실제 하드 데이터보다 더 과장되는 경향이 있다는 점을 명심하세요.
For more on this, read: What businesses do > what businesses say 🙊 and 4 sometimes-conflicting ways I’m thinking about the economy 😬😞😎🙃
이에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 기업들이 하는 행동 > 기업들이 하는 말 🙊 및 제가 경제를 바라보는 때때로 상충되는 4가지 관점 😬😞😎🙃
🏭 Business investment activity rose. Orders for nondefense capital goods excluding aircraft — a.k.a. core capex or business investment — increased 1.6% in August to a record $87.6 billion.
🏭 기업 투자 활동이 증가했습니다. 항공기를 제외한 비국방 자본재 주문(일명 핵심 자본재 투자 또는 기업 투자)은 8월에 1.6% 증가하여 사상 최고치인 876억 달러를 기록했습니다.
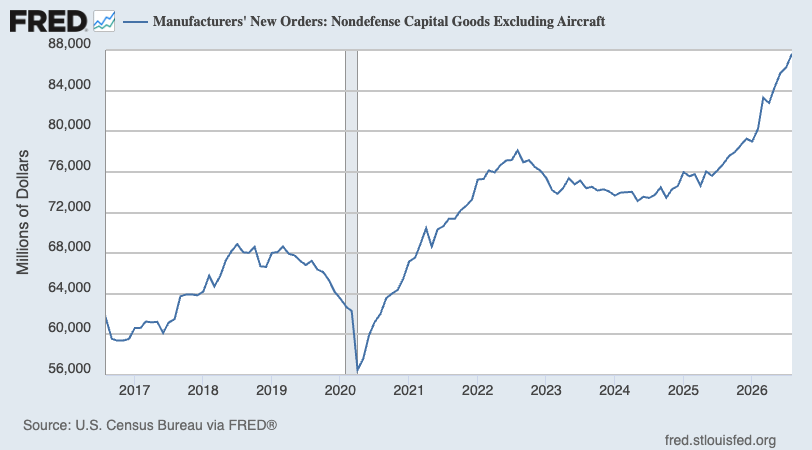
Core capex orders are a leading indicator, meaning they foretell economic activity down the road.
핵심 자본재 주문은 향후 경제 활동을 미리 보여주는 선행 지표입니다.
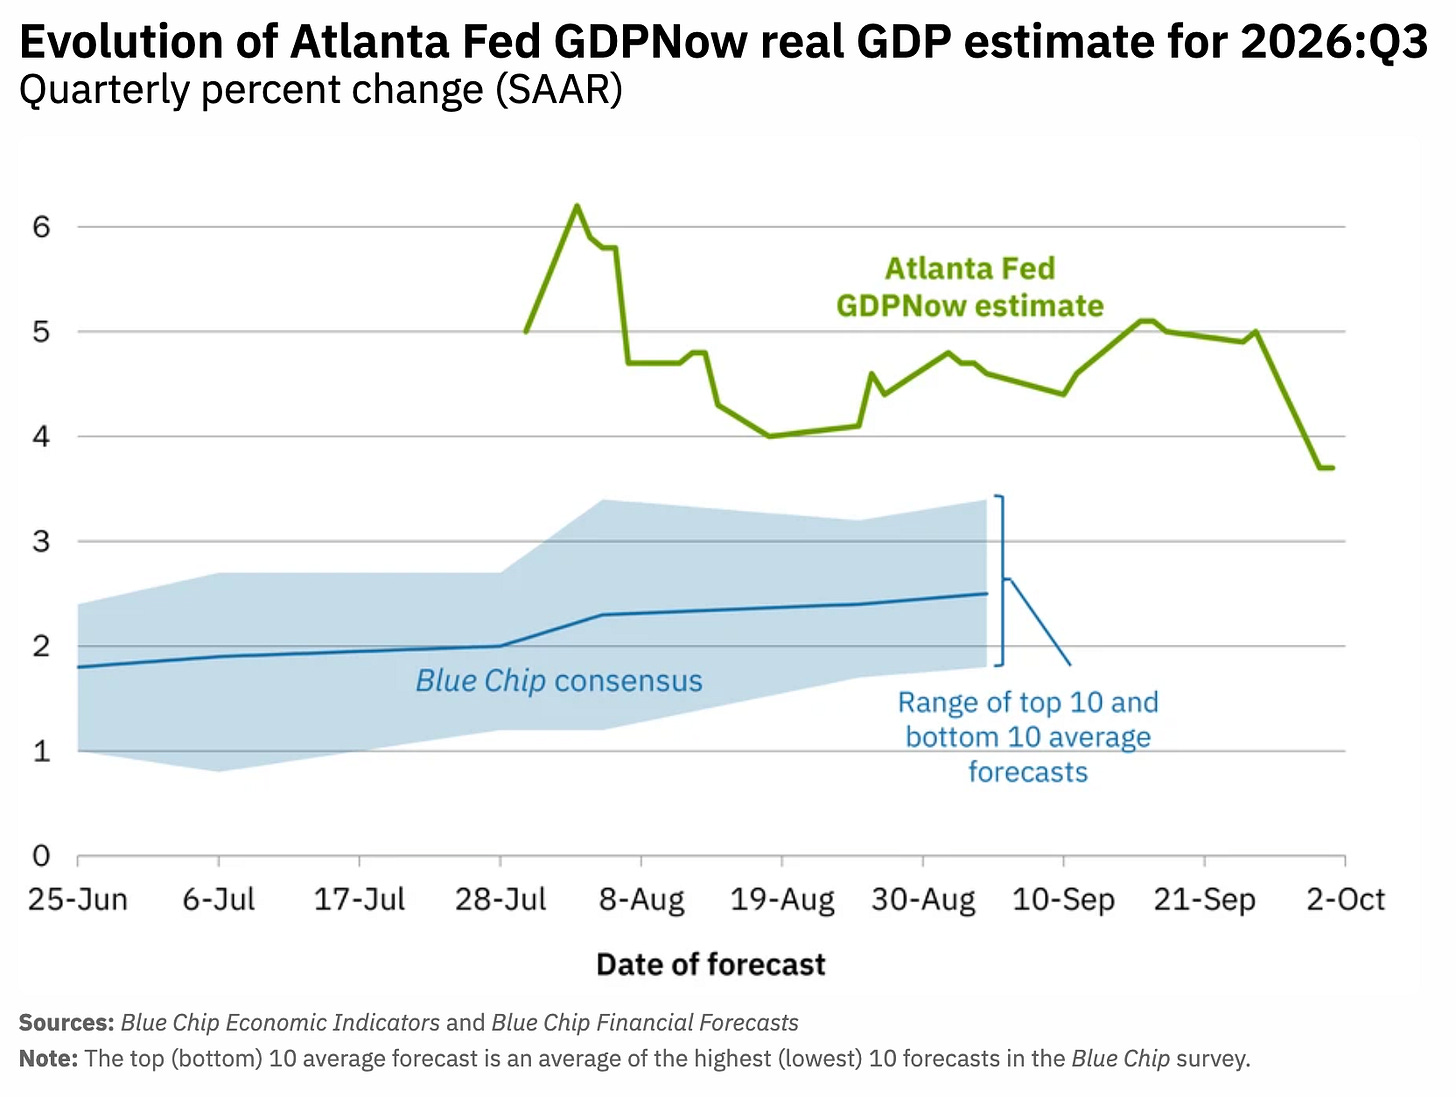
📈 Near-term GDP growth estimates are tracking positively. The Atlanta Fed’s GDPNow model sees real GDP growth rising at a 3.7% rate in Q3.
📈 단기 GDP 성장률 전망은 긍정적인 흐름을 보이고 있습니다. 애틀랜타 연방준비은행의 GDPNow 모델은 3분기 실질 GDP 성장률이 3.7%의 연율로 상승할 것으로 전망하고 있습니다.
For more on GDP and the economy, read: It’s too ambiguous to just say ‘the economy’ 🤦🏻♂️ and Economic data can often be both ‘worse’ and ‘good’ 🌦️
GDP와 경제에 대해 더 자세히 알아보려면 다음 글을 읽어보세요: 단순히 '경제'라고 말하기에는 너무 모호합니다 🤦🏻♂️ 및 경제 데이터는 종종 '나쁨'과 '좋음'을 동시에 보여줄 수 있습니다 🌦️
Putting it all together 📋
Earnings look bullish: The long-term outlook for the stock market remains favorable, bolstered by expectations for years of earnings growth. And earnings are the most important driver of stock prices.
📈 기업 실적은 낙관적입니다: 주식 시장의 장기적인 전망은 수년간의 실적 성장 기대감에 힘입어 여전히 유리합니다. 그리고 실적은 주가를 움직이는 가장 중요한 동력입니다.
Demand is positive: Demand for goods and services remains positive, supported by healthy consumer and business balance sheets. Personal spending activity remains at record levels. Core capex orders, which are a leading indicator of business spending, have been trending higher.
💡 수요는 긍정적입니다: 건전한 가계 및 기업 대차대조표를 바탕으로 재화와 서비스에 대한 수요는 여전히 긍정적입니다. 개인 소비 활동은 사상 최고치를 유지하고 있으며, 기업 지출의 선행 지표인 핵심 자본재 주문은 상승 추세를 보이고 있습니다.
Growth rates have cooled: While the economy remains healthy, growth has normalized from much hotter levels earlier in the cycle. The economy is less “coiled” these days as major tailwinds like job openings and excess savings have faded. Job creation, while positive, is not as hot as it used to be. It has become harder to argue that growth is destiny.
🌡️ 성장률은 둔화되었습니다: 경제는 여전히 건강하지만, 경기 순환 초기보다 성장세가 정상화되었습니다. 구인 건수와 초과 저축 같은 주요 호재들이 옅어지면서 경제의 '응축된 에너지'는 예전만 못합니다. 고용 창출 역시 순항 중이기는 하나 과거만큼 뜨겁지는 않습니다. 성장이 곧 필연이라고 주장하기는 어려워졌습니다.
Actions speak louder than words: We are in an odd period, given that the hard economic data decoupled from the soft sentiment-oriented data. Consumer and business sentiment has been relatively poor, even as tangible consumer and business activity continues to grow and trend at record levels. From an investor’s perspective, what matters is that the hard economic data continues to hold up.
🗣️ 말보다 행동이 중요합니다: 현재 우리는 딱딱한 실물 경제 데이터와 부드러운 심리 지표가 서로 디커플링(탈동조화)되는 기묘한 시기를 지나고 있습니다. 가시적인 소비 및 기업 활동이 계속해서 성장하며 사상 최고치를 경신하고 있음에도 불구하고, 소비자 및 기업 심리는 상대적으로 부진합니다. 투자자의 관점에서 중요한 것은 실물 경제 데이터가 계속해서 버텨주고 있다는 점입니다.
Stocks are not the economy: There’s a case to be made that the U.S. stock market could outperform the U.S. economy in the near term, thanks largely to positive operating leverage. Since the pandemic, companies have aggressively adjusted their cost structures. This came with strategic layoffs and investment in new equipment, including hardware powered by AI. These moves are resulting in positive operating leverage, which means a modest amount of sales growth — in the cooling economy — is translating to robust earnings growth.
📊 주식 시장은 곧 경제 그 자체가 아닙니다: 긍정적인 영업 레버리지 덕분에 단기적으로 미국 주식 시장이 미국 경제를 아웃퍼폼(초과 성과)할 가능성이 있습니다. 팬데믹 이후 기업들은 비용 구조를 공격적으로 조정해 왔습니다. 여기에는 전략적 감원과 AI 탑재 하드웨어를 비롯한 신규 장비 투자가 포함되었습니다. 이러한 조치들은 긍정적인 영업 레버리지로 이어져, 둔화되는 경제 속에서도 완만한 매출 성장이 강력한 이익 성장으로 직결되고 있습니다.
Mind the ever-present risks: Of course, we should not get complacent. There will always be risks to worry about, such as U.S. political uncertainty, geopolitical turmoil, energy price volatility, and cyber attacks. There are also the dreaded unknowns. Any of these risks can flare up and spark short-term volatility in the markets.
⚠️ 상시 존재하는 리스크를 염두에 두세요: 물론 안주해서는 안 됩니다. 미국 정치적 불확실성, 지정학적 소용돌이, 에너지 가격 변동성, 사이버 공격 등 언제나 우려해야 할 리스크는 존재합니다. 여기에 두려운 미지의 리스크(unknowns)도 있습니다. 이러한 리스크 중 어느 것이든 불거지면 시장에 단기적인 변동성을 촉발할 수 있습니다.
Investing is never a smooth ride: There’s also the harsh reality that economic recessions and bear markets are developments that all long-term investors should expect as they build wealth in the markets. Always keep your stock market seat belts fastened.
🎢 투자는 결코 순탄치 않습니다: 장기 투자자들이 자산을 구축하는 과정에서 경기 침체와 약세장은 누구나 예상해야 하는 냉혹한 현실입니다. 주식 시장에서는 항상 안전벨트를 단단히 매고 있어야 합니다.
Think long-term: For now, there’s no reason to believe there’ll be a challenge that the economy and the markets won’t overcome. The long game remains undefeated, and it’s a streak that long-term investors can expect to continue.
⏳ 장기적인 관점을 가지세요: 현재로서는 경제와 시장이 극복하지 못할 난관이 있을 것이라고 믿을 이유는 없습니다. 장기 게임은 여전히 패배한 적이 없으며, 장기 투자자들이 앞으로도 계속 기대할 수 있는 불패의 행진입니다.
For more on how the macro story is evolving, check out the previous review of the macro crosscurrents. »
거시경제의 흐름이 어떻게 진화하고 있는지 더 자세히 알아보려면 이전의 거시경제 엇갈림 요인(crosscurrents) 리뷰를 확인해 보세요. »



