Most stock-picking pros have been underperforming this year's rollercoaster ride higher

Source: https://www.tker.co/p/spiva-1h-2026-active-manager-vs-benchmark
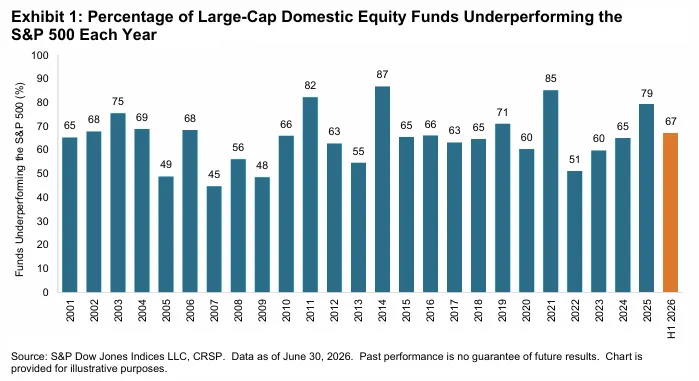
It remains tough to generate stock market returns that beat (or outperform) a passively managed fund tracking the S&P 500.
에스앤피 500(S&P 500) 지수를 추종하는 패시브 펀드의 수익률을 앞서거나(아웃퍼폼) 상회하는 주식 시장 수익을 올리기는 여전히 어렵습니다.
According to new data from S&P Dow Jones Indices (SPDJI), just a third of U.S. large-cap equity fund managers outperformed the S&P 500’s 10% gain in the first half of 2026.
에스앤피 다우존스 인다이시스(SPDJI)의 새로운 데이터에 따르면, 2026년 상반기 동안 S&P 500의 10% 상승률을 넘어선 미국 대형주 주식 펀드 매니저는 단 3분의 1에 불과했습니다.
“Compared with recent years, active managers faced a more supportive market backdrop, characterized by broader participation and stronger performance outside the largest stocks,” SPDJI analysts led by Anu Ganti wrote. “In our largest and most closely watched comparison, 67% of all active large-cap U.S. equity funds underperformed the S&P 500. It was an improvement from the 79% rate observed over full-year 2025, but these seemingly favorable conditions were still not enough for most managers to capitalize on.“
아누 간티(Anu Ganti)가 이끄는 SPDJI 분석가들은 "최근 몇 년에 비해 액티브 매니저들은 더 넓은 참여와 대형주 이외 종목들의 더 강한 성과를 특징으로 하는, 한층 우호적인 시장 배경에 직면했다"고 썼습니다. "가장 규모가 크고 가장 면밀히 주시하는 비교 군에서, 전체 미국 대형주 액티브 펀드의 67%가 S&P 500보다 저조한 수익률을 기록했습니다. 이는 2025년 전체 연도에 관측된 79%의 부진 비율보다는 개선된 것이지만, 이러한 겉보기에는 유리한 조건조차도 대부분의 매니저들이 수익을 내기에는 여전히 충분하지 않았습니다."
Indeed, more stocks have been moving independently of each other. But as we discussed in July, just because market conditions increasingly favor stock pickers doesn’t mean more stock pickers are beating the market.
실제로 더 많은 주식들이 서로 독립적으로 움직이고 있습니다. 그러나 지난 7월에 논의했듯이, 시장 조건이 점점 종목 선별 투자자들에게 유리해진다고 해서 더 많은 종목 선별 투자자들이 시장을 이기고 있다는 뜻은 아닙니다.
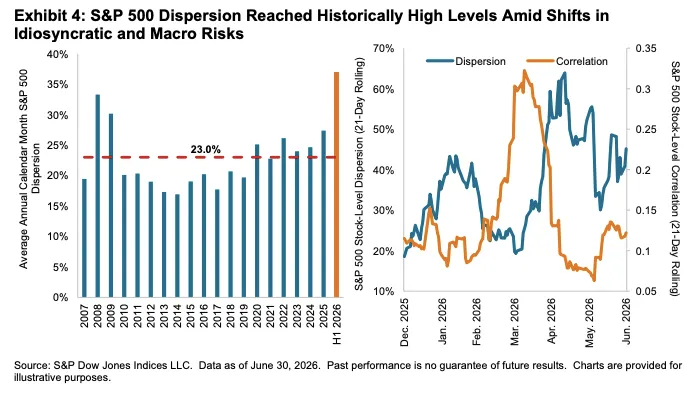
Here’s more on that from SPDJI’s report: “Conditions for stock selection were generally auspicious, but active managers had to contend with a shifting volatility landscape. Dispersion rose during the first two months of the year, however, idiosyncratic risks took a backseat to macro risks in March, as investors shifted their focus away from SaaS apocalypse fears and toward the war with Iran. Dispersion declined and stock-level correlations rose accordingly. Subsequently, easing geopolitical concerns and increased scrutiny faced by companies during the Q1 earnings season contributed to the return of company-level risk and a sharp rise in dispersion. The prospects for stock pickers in large-cap U.S. equities were most pronounced during May 2026, when S&P 500 rolling 21-day dispersion reached a high of 64%.”
SPDJI 보고서의 관련 내용 원문은 다음과 같습니다. "종목 선별을 위한 여건은 전반적으로 호조를 보였으나, 액티브 매니저들은 변화무쌍한 변동성 환경에 대처해야 했습니다. 연초 첫 두 달 동안에는 개별 종목 간 수익률 편차(dispersion)가 커졌으나, 3월에는 투자자들의 시선이 SaaS(서비스형 소프트웨어) 종말 공포에서 이란과의 전쟁으로 쏠리면서 거시경제적 리스크가 개별 기업 리스크를 압도했습니다. 이에 따라 종목 간 편차는 줄어들고 주가 상관관계는 높아졌습니다. 이후 지정학적 우려가 완화되고 1분기 실적 시즌 동안 기업들에 대한 검증이 강화되면서, 기업별 리스크가 다시 부각되고 종목 간 편차가 급격히 확대되었습니다. 미국 대형주 액티브 주식 투자자들에게 가장 유리했던 시기는 S&P 500의 21일 롤링 종목 간 편차가 64%로 최고치를 기록했던 2026년 5월이었습니다."
We’re now on track for a 17th consecutive year in which the majority of fund managers in this category have lagged the index.
우리는 현재 이 카테고리의 펀드 매니저 중 다수가 지수 성과를 밑도는 추세가 17년 연속으로 이어지는 기록을 향해 가고 있습니다.
This is probably assumed. But as you stretch the time horizon, the numbers get even more dismal. Over three years, 77% underperformed the S&P 500. Over five years, 89% underperformed. And over 20 years, 93% underperformed.
이전부터 짐작하셨을 수도 있습니다. 하지만 투자 기간을 늘릴수록 이 성적표는 더욱 참담해집니다. 3년 동안은 77%가 S&P 500보다 저조한 성과를 냈습니다. 5년 동안은 89%, 그리고 20년 동안은 93%가 지수를 밑돌았습니다.
To be fair, the goal of every fund manager and investor isn’t necessarily to beat some benchmark. Nevertheless, for active investors, seeing a low-cost index fund consistently outperforming may be disheartening.
공정하게 말하자면, 모든 펀드 매니저와 투자자의 목표가 반드시 특정 벤치마크를 이기는 것만은 아닙니다.럼에도 불구하고 액티브 투자자들에게는 저비용 인덱스 펀드가 꾸준히 시장을 아웃퍼폼하는 모습을 지켜보는 것이 낙담스러울 수 있습니다.
Past performance is no guarantee of future results 📉
It’s great if you or your fund manager have generated industry-leading performance in recent periods. However, outperformers rarely continue to outperform.
귀하 또는 귀하의 펀드 매니저가 최근 기간에 업계 최고 수준의 실적을 거두었다면 정말 훌륭한 일입니다. 하지만 우수한 성과를 낸 이들이 계속해서 뛰어난 성과를 거두는 경우는 드뭅니다.



